10 Expenses You Need to Cut Now for the Upcoming Economic Depression- The Reckoning Will Arrive Quietly!
Editor’s Note
Economists say nobody can date a recession, which is true and also the least useful thing they tell us, since a household does not need a date so much as a margin. What people can date is their own tightening — the cancelled service, the second car listed on a Saturday morning, the pantry that abruptly acquires a system and a rotation — and that tightening is already underway in ordinary kitchens where the arithmetic gets done after the dishes are washed, months ahead of any official confirmation.
Two questions sit under everything that follows: how much fixed weight can an ordinary family carry before one bad quarter becomes a ruined decade, and who decided the answer should be as much as a lender will allow? The second matters more, because nobody actually signed off on it, and because the answer has been quietly wrong before.
This piece is long on purpose, and it is written for people who would rather move early than move under duress. (Major sites are warning of a possible economic collapse in the coming years — watch this video to find out why.)
Cutting Weight Before the Storm: Why Households Feel the Break Long Before Economists Name It
The last time the ground shifted this way, in 2008, the earliest warnings came from the least credentialed places. The mortgage broker stopped returning calls. A neighbour sold a boat in June, which nobody thought about until October. When a plant trimmed overtime without announcing anything, the men on the floor noticed before the memos did. By the time the official word arrived, the decisions that would decide how the year treated each household had already been made by whoever made them, and everyone else spent two years catching up to a reality that had been visible, faintly, for months. Something similar is in the air now, minus the convenience of one dramatic event to point at, which makes it harder to argue about and considerably easier to ignore.
Being right about the future is less valuable than being early about your own exposure, and nobody needs a forecast to notice that fixed costs have crept up to meet income, that a savings account has been quietly subsidising the gap between the life a family leads and the one it planned, or that the whole arrangement rests on a single signature continuing to arrive. What follows is not a prophecy and does not pretend to be one, only a triage list ordered the way you would move if the ground started to give — fastest cuts first, then the slow, heavy, invisible ones that take years rather than weeks.
Four things are worth pinning down before the list, because they explain the order, and why some families will barely feel a downturn that flattens others.
▪ Fixed costs do not shrink when income does. A mortgage, a car payment, a card minimum and a nursery bill keep arriving in full whether or not the paycheck behind them arrives at all, so the damage in a collapse gets done by obligations rather than by prices. The family that can bend its obligations survives a shock that snaps the family carrying more of them, and income rarely decides which is which.
▪ Two households earning the same salary can sit in opposite positions. One holds a mortgage coverable on half a paycheck, drives something paid off and keeps a few months of cash within reach, while the other needs both incomes, carries a loan on the second car, services a card balance and keeps almost nothing liquid. From the street they look identical; only one has room to move.
▪ Cash is not the same thing as net worth. A retirement account feels like a cushion until it has to be tapped in a falling market, and home equity feels like one until the sale drags on four months and the buyer offers less than the last comparable. The only genuine cushion is the boring sort: money sitting somewhere reachable, doing nothing impressive, ready on a Tuesday.
▪ The window to act closes before the layoff, not after it. Once the notice lands, everyone in town is selling at the same moment, lenders tighten in unison and the family that waited pays the price of the crowd. Move while the paycheck still exists and you sell into a functioning market; move afterwards and you sell into a queue.
Here is where the last two collapses get specific, since generalities have a way of sliding off. Between 1929 and 1932 American equities lost roughly 89 percent of their value, around nine thousand banks failed and took depositors’ money with them, unemployment climbed toward a quarter of the workforce, national income fell by close to a third, and the federal government eventually shut every bank in the country for a week in March 1933 to stop the runs. Thirty years of habit dissolved in three, and the men who came through with their dignity intact were mostly the ones who owed the least. In 2008 the mechanism was faster and narrower but just as brutal in the personal register: Lehman Brothers filed on 15 September, credit markets froze within days, the S&P 500 fell about 57 percent from its 2007 peak to its March 2009 low, roughly 8.7 million jobs vanished and home prices dropped by around a third, leaving millions owing more than their houses were worth and unable to sell or refinance their way clear.
(A sequence that actually happened, and deserves remembering, because it answers the question of whether money in a bank is really money in your hand. In December 2001 Argentina froze bank withdrawals under a set of limits the press called the corralito, and savers discovered that the balance on the statement was real but unreachable; when the currency peg broke weeks later, dollar deposits were converted at a rate savers had not agreed to. In March 2013 Cyprus imposed a haircut on uninsured deposits above €100,000 to fund a bank rescue, and money that had been guaranteed in ordinary conversation turned out to be a claim rather than a possession. In June and July 2015 Greece closed its banks and capped ATM withdrawals at €60 a day for weeks, and pensioners queued outside branches for their own money. None of these was a collapse of the kind the history books describe, and every one of them was a collapse for the household living through it.)
What the record keeps saying, in the grand versions and the small ones alike, is that pressure arrives as a sequence rather than a single blow. Employment goes first, in hours cut before jobs are lost and overtime that quietly stops, credit follows as approvals automatic in spring are refused by autumn, and assets come next, when the house and the fund that were meant to be the safety net turn out to be worth less than the family believed. Fixed obligations, which never tightened at all, keep arriving in full at the worst possible hour, which is why they matter more than the things people argue about. The trouble with the interval between the first sign and the general recognition is that families make their biggest decisions inside it, in the dark, on the reasonable assumption that the last ten years will run for ten more.
So the work is to shed weight now, while the ground still feels solid and selling is still easy. The order below runs from cuts that take an afternoon to cuts that take a year, and it runs that way deliberately, because the small fast ones create the margin that the big slow ones are paid out of; skip the sequence and the margin never appears, since the other costs keep absorbing whatever surplus shows up.
What follows, then, are the ten places a household bleeds, and what to do about each. Two dots, and then the list:
1. Kill the Second Car First, Because It Bleeds While Parked
Nobody questions the second car, which is exactly what makes it the best place to start. A spare vehicle feels prudent, and the phrase in case we need it covers an enormous amount of ground, but the money it consumes is nearly invisible because it never arrives as one honest bill. The payment is the part people notice, and even that fades into background noise once it has left the account on the same date for four years running, while everything else goes uncounted — insurance on a machine that sits, registration and inspection, a battery that dies every February because the car never moves enough to stay charged, tyres that dry-rot from standing still and oil changed on something that covered four thousand miles in a year. Depreciation sends no invoice and erases value steadily, so a spare car can quietly cost a household thousands annually while doing almost nothing.
Trouble is that a downturn makes the arithmetic worse at precisely the moment the escape hatch narrows, because a weakening economy is when buyers thin out and everybody tries to sell at once, which is what happened across the United States in 2008 and 2009 when used lots filled with the vehicles of people who had waited too long and prices sank under the weight of the supply. Sell while the market still functions and you get a fair number; wait three months past the layoff and you take whatever the queue offers.
The useful question is not whether the second car is convenient but how often it actually turns a wheel. Something that sits all week and rolls out for the occasional errand is less a means of transport than a hobby with a monthly fee attached, and banking the cash from it usually reveals within a month how little it was missed. Two adults genuinely commuting in opposite directions are a different case entirely, and there the move is simply to stop paying to maintain an idle machine — drop it to the cheapest sensible coverage, take it off the road if the rules allow, and treat it as a backup rather than a daily driver.
Harder than selling is refusing the upgrade reflex, since the car already in the driveway is almost certainly fine and the newer one mostly repairs a feeling. In the years before 2008 families traded up every few years as a matter of course, financing the difference each time, and the cycle felt painless because the shortfall was rolled forward rather than paid off; when income tightened the arrangement revealed itself as a treadmill, with the family that keeps a car two extra years spending nothing to do so and the family that replaces on schedule spending thousands to stay current. During a squeeze that difference stops being cosmetic.
Something quieter explains why people who prepare seriously tend to own one good vehicle rather than three mediocre ones. A single reliable car means one set of tyres, one insurance bill, one registration, one machine you can actually stay ahead of and one point of failure instead of four, so simplicity costs less and breaks less. What makes this the first cut on the list rather than the last is that it works in ordinary years too, which means the household doing it now is not gambling on a crash so much as collecting a benefit whether or not one arrives.
A caution keeps the rule from hardening into dogma. Rural households where the nearest shop is twenty minutes away and public transport barely exists are a genuine exception, and so are homes with a disabled member or a trade that requires carrying tools, because there the second vehicle sits closer to necessity than to luxury. The instruction is not always sell the second car, it is know exactly what the second car costs you and decide whether the use justifies the price — and most families, doing that sum honestly, will find the answer uncomfortable.
Discover the 3 Sure-Fire Signs That Could Signal a Major Crisis in 2026 — and Why More Americans Are Starting to Pay Attention. The Video Below Takes a Closer Look at What May Be Coming and the Signs You Shouldn’t Ignore.
2. Subscriptions, or the Tax Nobody Voted For
Money now leaves accounts in the middle of the night, which is a recent and slightly strange arrangement, and it began innocently enough. Streaming arrived first, each service cheap enough to dismiss and each promising roughly what the last one promised, cloud storage followed once phones filled up, and behind it came the app that tracks the other apps, the premium tier upgraded for a single series and never downgraded, the fitness app, the meditation app and the news subscription taken out during an anxious month and forgotten by the next. Individually each charge is small enough that cancelling feels like fussing over pennies, and together they form a monthly tax that buys almost nothing anyone would notice losing.
Inertia is the entire business model, and it is worth seeing how deliberately that inertia gets built. A one-time purchase asks you to decide once; a subscription asks you to decide only when you leave, and leaving involves friction, and friction is where the profit lives. Companies know a meaningful slice of their subscribers are dormant — still paying for something they stopped using — and they design around the dormancy rather than against it, keeping the monthly figure below the threshold at which a person bothers to act. The enemy, then, is never any particular service, it is the absence of a decision.
Clearing it takes one hour and two or three recent statements. List every recurring charge, ask of each whether it was touched in the last ninety days, and cancel whatever fails on the spot rather than waiting for some contract to expire out of politeness; whatever survives deserves to be kept without guilt, since a real habit is worth its price. Annual plans deserve the same scrutiny, because a yearly charge that surprises you when it lands has already told you what it is, and a quarterly review keeps the list from quietly rebuilding itself during busy months.
Under pressure the value of this cut becomes obvious, since subscriptions are the easiest thing in a household to switch off and therefore the first line of defence when income dips. A family that has already pruned can trim again in an afternoon, while a family that never looked discovers at the worst possible moment that it is paying for three services it forgot and two it barely uses. There is also something almost philosophical about the category, because it is the purest version of the problem this whole piece describes — a fixed cost, renewed automatically, that the household never actively chose a second time after the first click.
A behavioural trap catches careful people here too. Once a subscription has been paid for a while the household starts to feel entitled to it, and cancelling registers as a small loss rather than a small saving, which is the same sunk-cost instinct that keeps people in bad gym memberships and half-finished courses. The money is gone either way; the only live question is whether the next month is worth its price, and seen that way most dormant subscriptions are obviously not worth it and the decision becomes easy.
3. Memberships, Gyms, and the Loyalty You Keep Paying For
January is the most profitable month the fitness industry knows, and the reason has nothing to do with exercise. People sign up with conviction and then keep paying out of loyalty long after the conviction fades, and the same pattern repeats across warehouse clubs, subscription boxes, professional associations and that one membership taken out for a wedding and never cancelled, which means a whole corner of the economy runs on enthusiasm at the front door and inertia at the back.
Auditing it is simple and slightly brutal, because only one question matters: was this used in the last ninety days. A no means cancel today, and a yes means keep it without punishing yourself, since abandoning a membership you actually use is false economy. Warehouse clubs deserve their own paragraph, because they cut in both directions — saving real money for a large household that genuinely buys in bulk while turning into a place where a small household buys forty items it did not need because the unit price looked good.
Psychology sits under all of this, and it is the same psychology running through the rest of the list. A membership is a commitment made by one version of you on one hopeful day and paid for by every later version of you, whether or not the hopeful day still describes anything real; the January gym assumes a person who will go three times a week, and the version of you who actually turns up twice a month is subsidising the fantasy. Recognising that is not failure, it is just accounting, and accounting is what keeps a household solvent when the environment turns.
Once income wobbles, memberships are the second thing to go after subscriptions and for the same reason, which is that they cancel quickly and the loss is psychological rather than practical. Test each one against real use and the dead ones fall in an afternoon, whereas the family that never looked finds itself paying for loyalties it can no longer afford. Run the arithmetic on what you truly consume rather than on what a full trolley makes you feel, and be the one who cancels first, because membership models depend on a baseline of discretionary spending that thins out broadly whenever incomes tighten.
4. Your Phone Is Not Broken
One sentence dismantles an entire industry. Your phone is fine. The treadmill runs on a manufactured belief that last year’s machine is somehow broken, when in reality it will serve two or three more years with a replaced battery, because firms build obsolescence into both hardware and software and marketing exists to make the old feel inadequate long before it fails. Step off the wheel and the device keeps working while the pressure simply evaporates.
Stepping off is not the same as refusing to buy. It means going used, choosing refurbished, or picking up an older generation once the newer one lands, so that a two-year-old flagship does everything the current model does at half the price and a refurbished laptop with a fresh battery is indistinguishable from new to anyone not running benchmarks. Repair completes the equation, since a screen, a battery, a keyboard or a hinge each costs a fraction of a replacement and keeps a working device out of a drawer, and what actually breaks in practice is rarely the machine but the willingness to tolerate a small flaw.
A wrinkle here is plausible rather than certain, in that the used and repair market tends to strengthen exactly when money tightens, so leaning on it now puts a household ahead of the curve rather than behind it, though whether that holds in any given downturn is a guess rather than a rule. Either way the discipline costs nothing and pays in ordinary years too, and it echoes something older, because families through the Depression did not buy new things so much as make old ones last, and the ones good at making do were the ones who kept a little money in the tin.
A social cost hides in the upgrade habit as well, and it is worth naming. New devices announce themselves, neighbours notice, colleagues notice, and the family that replaces its phones on schedule holds a certain standing that the family on two-year-old models does not. Maintaining that standing is cheap during good times and a running expense during a squeeze, when it competes directly with food and rent, and the household that has already stepped off tends to find that nobody noticed the difference and that the money saved is entirely real while the status given up was mostly imaginary.
Nothing here should harden into dogma, though, because if a device is genuinely the tool of a trade — a photographer’s camera, a programmer’s laptop, a designer’s monitor — then buying up can pay for itself and the discipline should bend accordingly. The mistake is buying up for standing while telling yourself it is for work, and the family that can tell the two apart will save more than the family that cannot, without feeling like it is falling behind, because it is measuring the right thing.
5. The Convenience Premium: Delivery, Coffee, and the Cost of Being Tired
Convenience is the most expensive ingredient in ordinary modern life and it hides inside habits people defend as normal. Coffee made at home costs pennies while the same coffee made by a stranger costs five dollars and a walk, and plenty of people buy two a day while insisting there is nothing left to save; delivery is worse once the maths is done, since a meal that cost twelve dollars at the counter reaches the door at close to thirty after fees, tip, service charge and the small-order penalty. Restaurants are not the problem so much as the markup is, and the markup is worth paying when you actually want the experience and much less worth paying when you are simply tired.
None of this demands austerity. Cooking five nights instead of two and brewing at home returns a genuinely meaningful sum to an account you had forgotten, and the habit doubles as a survival skill, because someone who can cook from basic staples is insulated against restaurant inflation, supply hiccups and the particular misery of a tight month. A handful of meals you can make blind, a stocked spice shelf and a Sunday spent batch-cooking will do more for a household’s resilience than most of the gadgets sold to it.
The premium has been widening as delivery platforms matured, though the exact share varies by city and by year, so any single figure deserves suspicion even when the direction is clear. Cheap labour, cheap fuel and cheap logistics built the convenience economy, and if any of those tighten the premium widens further and the household that already cooks at home feels it least. Food waste belongs in the same conversation and usually gets left out of it, since a typical household throws away a startling share of what it buys, and the fix — plan the meals, buy to a list, eat the leftovers — costs nothing but attention. Paying once for food and then binning part of it is the worst kind of leak, because you have paid twice.
Down the last two downturns this is the category households cut first and hardest, for the simple reason that it is the most elastic, and a family can move from four restaurant meals a week to one with barely a twinge once the cooking habit is rebuilt. The household that never learned to cook is stuck paying restaurant prices for every meal because it has no fallback skill, which makes cooking less a way to save money than a way to convert time into resilience, and that is exactly the trade a downturn demands.
Danger lives in the accumulation rather than in any single purchase. An occasional dinner out is harmless; the problem is the pile of small, frequent, convenient transactions that individually cost little and together rival a utility bill, so the family that counts the coffee, the lunch, the delivery and the takeaway as one line rather than four separate habits is usually shocked by the total. Once the total is visible, cutting it becomes a choice rather than a deprivation, and the cooking skill turns the choice into something closer to a pleasure than a punishment.
6. Groceries, the Pantry, and the Only Cut That Feeds You
Inflation bites hardest at the checkout, which is why small repeatable decisions in a supermarket compound faster than almost anything else in a budget. Brand loyalty is a strange luxury, because in plenty of categories the store brand comes off the same line as the branded one and the only difference is the label and the price, so shopping the perimeter of produce, meat and dairy while treating the middle aisles as a controlled zone cuts a food bill without eating worse. Buying in bulk helps within limits — deep on what you consume and can store, shallow on what will spoil or gather dust.
From there the conversation moves naturally to the pantry, and to the thread of preparation running under this entire piece. A shelf of staples bought on sale, from rice and beans to pasta, tinned goods, oil and coffee, hedges against both price spikes and supply wobbles, and unlike most hedges it improves with use provided you rotate it, cook from it and refill it. Even a few pots on a balcony turn a little money into a little food and a great deal of skill, and they teach the most useful truth of a downturn, which is that food comes from work rather than from shelves. Waste returns here as the quietest thief in the house, since buying to a list and eating the leftovers costs nothing and recovers money already spent.
Two caveats belong here. Savings from generic substitution vary by category and region, so some generics are identical and a few are not, which is a reason to test rather than assume; and a stockpile turns into a hoard if it is bought faster than it is eaten, which ties up cash that might be needed elsewhere. Buy deep on what you actually use, rotate faithfully, and let the shelf behave like a savings account whose balance is measured in meals.
Under pressure this category does something no other one does, which is feed you. When income falls, the household that cooks, stocks and wastes little absorbs a shock that sends a less prepared family straight to the food bank or the credit card, and because groceries are the one expense that cannot be cut to zero, the family that has optimised them starts every squeeze from a stronger position. A full pantry and a working kitchen are, in the strictest sense, insurance, and the premium is paid in attention rather than money.
Worth adding, because the prepper instinct often overreaches: the goal is not a bunker. Ten days of shelf-stable food you actually like, a few litres of water per person, a working torch, a decent knife, a first-aid kit with the things you genuinely use, and a printed list of the numbers you would need if the phone died — that combination handles most of what an ordinary disruption throws at a household, and it costs less than a single monthly delivery habit.
7. Travel, Morale, and the Vacation You Think You Owe Yourself
Travel is where good intentions and bad arithmetic meet, because after a hard year the trip you feel you owe yourself can quietly wreck the budget you were proud of. It arrives as one large discretionary hit at exactly the moment the future looks least certain, and yet none of that makes travel foolish, only the timing and the method worth a rethink.
The cost stack is bigger than the flight, since flights, rooms, food, transport, activities and the extras nobody budgets for all scale with peak dates. Cheapest single lever is the calendar, because travelling off-season costs a fraction of the identical trip in July, and the next is proximity, because somewhere drivable skips the airfare, the rental and the airport tax on your time. Staying with people instead of paying for a room, booking early and treating the destination as a place to live rather than a checklist all push the number down without pushing the joy out.
Why bother at all when money is tight? Because morale is a real asset and a collapse is long, and a household that does nothing pleasant will grind itself down and then spend impulsively to recover. Two modest trips usually beat one grand one, in cost and in how they spread relief across a hard year, and while the exact saving depends on where you start, the principle holds — the same joy can be had for less if you shop the calendar and the map.
A subtler point sits underneath the psychology of scarcity. When money is tight the temptation is to cancel everything that feels optional, and travel feels the most optional of all, but a household that cuts every pleasure turns grim, and grim households make worse decisions because deprivation has a way of producing sudden expensive binges. Keep one small trip in the year, planned and affordable, and you get the morale benefit without the budget damage; travel done cheaply is not a luxury to be eliminated first, it is a small maintenance cost for the household’s mood.
8. Interest, the One Expense That Grows Teeth
Interest is the only item on this list that expands on its own, which makes it less a leak than a fire. A card balance at twenty-something percent means you are paying for last year’s dinners with next year’s paycheck, and the minimum payment is engineered to keep you there as long as possible, since a minimum is designed to preserve the balance rather than kill it. In a downturn debt is what turns a bad month into a catastrophe, because when income drops the interest does not care and the collector does not wait.
Strategy here is unglamorous and effective. Rank the debts, attack the most expensive first with every spare pound until it dies, then roll that payment onto the next; if the psychology of a quick win matters more to you than the arithmetic, take the smallest balance first instead, because both approaches work and the best plan is the one you actually finish. Clearing the cards is only half the job, since the harder test comes afterwards and consists of resisting the urge to refill them, and being debt-free in a shrinking economy is its own quiet kind of wealth, unfashionable and worth more than anything you can display.
Refinancing deserves a mention with a caveat attached, because it is where fact and guesswork tangle. Holding a loan well above today’s rate means refinancing can lower the payment, but it often stretches the term and adds fees, which makes it a trade rather than a free lunch and puts total cost ahead of monthly figure in importance. Should a downturn force central banks to cut, refinancing gets cheaper for those who still qualify — except qualification tends to tighten precisely when people need it most, which is the cruel symmetry of credit.
Sitting so late in the list is deliberate, since debt is the hardest item to fix quickly. A car sells in a fortnight, subscriptions cancel in an afternoon, groceries optimise in a week, and all of that buys the room that paying down debt requires, whereas a household that attacks the debt first finds the room never appears because the other costs keep absorbing the surplus. Cut first, then pay, and the balance actually shrinks instead of merely surviving.
Something else about debt and survival rarely gets said: an emergency fund and a paid-down card are the same defence seen from two sides. Cash stops you reaching for the card in the first place, and a clear card stops the interest from eating the cash you just built, which is why the two should move together rather than one being finished before the other starts.
9. Housing, the Box That Flatters You and Locks You In
Housing is the largest line in nearly every budget, which is exactly why people avoid touching it. A home is identity as much as shelter, and downsizing feels like a demotion even when it is really a promotion into breathing room, but the arithmetic does not care about feelings, and a payment that felt comfortable on two incomes in a rising market becomes a noose the moment one paycheck disappears, because the payment is fixed and does not adjust itself downward when life does.
Clearest lesson available comes from 2008, and the detail is worth retelling. For years lending loosened and homes sold on the promise that prices only rise, so families stretched to the limit of what they could borrow, treating the maximum a bank would lend as the amount they should spend; when prices fell by roughly a third and credit tightened, households that had stretched found they owed more than the house was worth, could not sell without a loss and could not refinance without equity, and the stretch that had looked like ambition became the thing that drowned them. Owning is not the problem, borrowing to the maximum is, and borrowing to the maximum is a bet.
Cold eyes on your housing this year repay the effort. Renters should price a smaller place one neighbourhood over, where the saving is often larger than people expect and the loss smaller, and owners under strain should weigh downsizing, a lodger, or refinancing while reasonable terms still exist. Maintenance and utilities scale with the size of the box, so a smaller home saves on far more than the mortgage, and there is a plausible if uncertain play in leaving an expensive metro for a cheaper one where the same remote salary stretches further — powerful if remote arrangements hold, risky if they are the first thing an employer claws back. A house that leaves you breathing room beats one that leaves you impressive.
Emotional weight is heavier here than anywhere else on the list, which is why the decision gets delayed past the point of wisdom, and a family will spend months agonising over a car while taking years to seriously consider the house that costs ten times as much. Part of it is that the home holds the memories and part of it is the fear of what the neighbours will think, both entirely real and neither visible on a spreadsheet, and the household that can hold numbers and feelings at the same time — acting on the numbers without pretending the feelings are not there — is the one that comes through with its finances and its dignity intact.
10. Lifestyle Creep, the Bill With No Statement
Hardest expense to cut is the one with no line item, no statement and no single charge to cancel. Lifestyle creep is the slow ratchet by which every raise becomes a new baseline and every promotion a bigger car and a better address, until a household earning double what it did five years ago still saves nothing at all, and the competition underneath is not with your younger self but with neighbours who are also stretched and also pretending.
Mechanism is well understood, because people adapt fast to any improvement, so the larger house and newer car stop feeling like luxuries within weeks and start feeling like the floor, and that adaptation is the ratchet. Break it deliberately by deciding a number to live below rather than a number to reach, and let the difference pile up somewhere reachable, automatically if possible so the ratchet works for you instead of against you; when the depression arrives, if it does, the family that never let lifestyle outrun income barely notices, while the ones chasing appearances sell the car, the house and the story they told themselves about who they were.
Unlike the second car or the subscriptions, creep leaves no clean receipt, which makes the fix behavioural rather than transactional and, for the same reason, the most durable of the ten, since a habit built once keeps paying without further decisions. It also rewards honesty more than the others do, because nobody is auditing a family’s choices from outside — the neighbour with the new car is not judging the family that kept the old one, the judgement is internal and almost entirely optional.
Social comparison deserves one careful thought, since it is not always wrong. Keeping pace with peers sometimes buys access, connections and opportunities that a more austere household loses, and a family living far below its means can find itself cut off from networks that matter. The trick is knowing which comparisons are worth the cost and which are pure habit, and the family that can tell the difference spends where it gains something and saves where it gains nothing, without either chasing every neighbour or withdrawing from the world.
What Comes Next, and How to Sleep Through It
Step back and the ten items collapse into a single idea. Fixed costs do not shrink when income does, so the space between the two is what separates a bad year from a ruined one, and every burden above was chosen for that reason — each a recurring drain that can be reduced without much reducing your life, none of them requiring genius, only the willingness to look at your own spending with a cold eye and ask which parts were building something and which were noise.
Where the next few years actually go is genuinely uncertain, and it helps to keep the levels straight rather than blend them. In the likelier path, pressure stays slow and grinding: modest growth, stubborn prices, jobs that feel less secure every year, governments that borrow and spend and keep the leverage they took in the last emergency, and a quiet erosion of the things that used to be automatic. A darker path involves a sharper event, a credit rupture or a market break that turns a slow leak into a burst pipe, and both paths reward the same preparation, which is the quiet beauty of doing the work now rather than later.
Picture the darker path in ordinary terms, because it is easier to dismiss as abstraction than to face as a sequence of Tuesdays. A plant announces layoffs in spring and the household that loses a paycheck is one of thousands; the first month is covered by savings, the second by trimming, and the trimming is easy because the family already lives below its income; by the third month the mortgage, the insurance and the groceries all arrive as usual and get paid, because the pantry is full, the subscriptions are gone and the second car was sold last year for real money. Across the road a household earning more is struggling, since its fixed costs never budged and its savings were thin, and every option now in front of it — dump the car at a loss, borrow from family, let a payment slide — got harder for having been postponed. Same town, same layoff, different outcomes, and the difference was built quietly months earlier by people who read the room before it creaked.
Nothing above promises that the careful family escapes unharmed. Some shocks are big enough to hurt everyone, luck still matters, and the best-prepared household in the world can still lose a job it loved. What preparation buys is not immunity but options, and options are the whole difference: the prepared family chooses which suffering it accepts while the unprepared family has its suffering chosen for it, which is worth more than any single cut on the list, because options are what let a household walk into a bad year with its dignity and its possibilities intact.
Then there is the part that only preppers tend to say out loud, and it deserves saying because it is true. Money is the first layer of resilience and it is not the last, so the household that also has a little water, a little food, a working torch, a few tools and one skill that produces something — cooking, growing, mending, building, fixing — is holding a buffer no bank can freeze. Add a small circle of people who would actually turn up if the power went out for a week and you have the thing that separates discomfort from disaster, because the collapse the history books record is always, at ground level, just neighbours helping neighbours through a stretch that the officials eventually name.
Depressions are not made of numbers so much as of the moment ordinary people, one by one, realise the world has already changed. Families who come through best are rarely the ones who predicted the crisis with perfect clarity; they are the ones who, months before it mattered, quietly shed the weight they never needed to carry and walked into the storm lighter than everyone around them. That is the whole of it, and it is available to anyone willing to spend a Saturday with a bank statement and a bin bag.
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
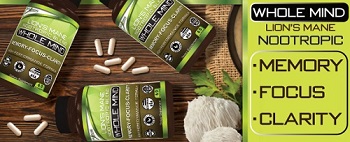
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,835,941,352 |
| Stories: | 8,726,464 |
Whistler Blowers, Insiders

