The Gift

Is it a Trojan horse?
By the way, that’s quite a yarn. After a decade of war, the Greeks couldn’t bust into Troy. So clever wag Odysseus had a giant hollow horse made, then stuffed it with elite fighters including himself.
The Greeks packed up, sailed off to a nearby island and appeared to have given up their siege. The lone soldier they left outside the city told puzzled Trojans the horse was a peace offering. They bought it. Rejoiced. Drank and made merry all night. And in the morning were massacred.
And this brings us to your RRSP.
Buried in Thursday’s budget was a gift from the feds. At least it looked that way. Ottawa has decided to scrap the RRIF – the registered retirement income fund – which is what your RRSP must turn into at age 71. If not, the whole shebang becomes taxable income. As wrinklies know, Canadians are obligated to withdraw a minimum amount annually (it starts around 5%) which is added to taxable income. (That minimum escalates with age.)
This conversion of an RRSP into another thing takes time and effort. Many are truly surprised when they hit 71 to learn of the requirement. An equal or greater number have little clear idea what a RRIF is, or that they can move their investments from one pot to another without liquidating any.
But Carney says forget about all that. It’s over. Instead, an everlasting, eternal RRSP.
“Canadians should be able to confidently manage their retirement savings without having to navigate unnecessary rules or move their savings between different accounts as they age,” said the budget. And here is the action…
“Budget 2026 announces the government’s intention to merge the tax rules applicable to RRSPs and RRIFs, introducing an “RRSP-for-life.” This would eliminate the need to convert an RRSP to a RRIF at age 71. It would also allow a surviving spouse or partner to become a successor holder of an RRSP and simplify tax-free transfers to qualified survivors after the death of the account holder. This would not change minimum withdrawal requirements after age 71.”
The change isn’t immediate. Everybody has to talk for a while first, But rest assured it will happen, maybe made into law next year.
There are implications, since the first major change to Canada’s system of retirement savings since finance minister Champagne was in short pants. For example, it changes how you can pass things to your spouse when your best-before date arrives. Currently you’re allowed to designate your squeeze as a ‘successor holder’ only for RRIFs and TFSAs, not registered retirement accounts. But not for long.
Huh? What’s the difference between a beneficiary and a SA?
It’s simple but meaningful. A bene receives the funds as a non-taxable payment, and the account dies along with its registered owner. But a successor holder actually takes over the entire account as a new registered owner, so the assets inside are not sold. So with a SA, investments keep on growing, with none of that growth taxed. For a beneficiary, growth on assets after the date of death is taxable, and it could take months to pay them out.
With the SA designation in place, a new lifetime RRSP would become the property of your spouse when you die. Seamlessly. It could be be held separately or merged with his/her registered account. All dividends, gains, growth stayed untaxed.
Remember that anyone can be a beneficiary. Only a spouse (or equivalent) can be a successor holder. Both escape probate and the CRA. But the SA is more tax-efficient and painless.
Part of what the feds are doing, then, is to make estate planning simpler, easier, less taxed. By eliminating the RRIF account entirely the process of passing wealth along becomes less complex. What the feds are not ding is ending the requirement to suck off taxable income after age 71.
Also not changing is the rule that RRSP contributions end in the year you turn 71, regardless of income – but unchanged is the ability to contribute to a spousal plan until your babe hits that age. So, obviously marry young.
Will pension-splitting survive? What happens next?
The RRSP-for-life proposal has given rise to issues that must be worked out. Will wrinklies still be allowed to pension-split with their spouses, trimming the overall family tax bill? Will withholding taxes on withdrawals be kept in place? What’s the impact on insurance companies that do a big business converting RRSPs into annuities? How about the zillions of existing RRSPs that name beneficiaries – do the banks and others have to repaper them all to turn them into SAs?
And then biggie: does messing with the retirement structure signal that Carney has a far larger agenda for dealing with runaway senior benefit costs? Will OAS – the largest expenditure the feds face – be in the crosshairs? Will we stop handing out money to people who don’t need it, and lower the clawback threshold? Will RRSP contribution limits be pushed far higher (like to 30% of income rather than 18%) to encourage personal savings? Will TFSA income in retirement be made taxable above a certain income level (it’s now utterly tax free for everyone)?
Without a doubt, the current system benefits the wealthy. It’s also unsustainable.
Yes, this change is good. But they’re still Liberals. Even bearing gifts.
About the picture: “Hi Garth, I am sending a few dog photos I’ve taken in the last few days while traveling in Mexico,” writes Owen. “Happily your blog helps keep me sane in these topsy turvy times. Thanks and take good care!”
To be in touch or send a picture of your beast, email to ‘[email protected]’.
Source: https://www.greaterfool.ca/2026/11/08/the-gift-6/
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
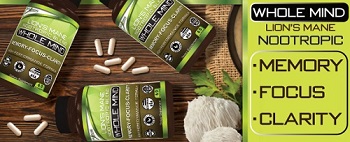
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,837,887,464 |
| Stories: | 8,734,289 |
Whistler Blowers, Insiders

