NYU Tax Policy Colloquium: Michael Love's Tax Policy in a World With Complex Firms: A Pigouvian Approach
Yesterday’s colloquium paper was Michael Love’s Tax Policy in a World With Complex Firms: A Pigouvian Approach, which is forthcoming in the Virginia Tax Review. It addresses the problem of complex business structures, in particular those conducted in partnership form, that have overwhelmed US tax enforcement since the IRS simply lacks the resources to audit them. This problem is so great, at present, that the IRS not only can’t do any meaningful enforcement of the businesses that are conducted via complex partnerships, but can’t even estimate the tax gap in this sector.
An interesting small fact that the paper mentions in passing relates to the frequency with which the statute of limitations runs out on partnership audits, when they even happen to begin with. What’s interesting about that is the fact that, in other settings, often the taxpayer will simply consent to extending the statutory period at the IRS’s request. This of course happens, not out of a spirit of fair play, but because the IRS can credibly say: Either you grant us the extension or we will simply issue a deficiency finding based on what we have right now. Evidently no such credible threat could be issued in partnership cases where the IRS remained too far from really understanding anything that might have been going on.
Anyway, the paper suggests two main tools in addressing the enforcement problem. The first is a Pigouvian tax on the costs of auditing these firms. The analogy is to a Pigouvian pollution tax. Factory emits smoke causing $X per cubic meter (or whatever) of smoke issued, so it is charged $X per cubic meter actually emitted. Here, when any complex (to review or figure out) aspect of firm structure or transactions would require $X of IRS audit expense to be audited properly, that generates a fee of $X.
The second is a classic Bentham/Becker penalty adjustment for deficiencies that the IRS finds, scaled up to reflect the probability of detection. Thus, for a deficiency of $X, if there was only a 20% chance that it would be found, the taxpayer has to pay $5X. This would cause a risk-neutral firm to act the same way as if the deficiency were certain to be found.
The paper convincingly argues that one would need both of these instruments, not just one of them, to address the incentive issues here properly. The big problem is that, even leaving aside questions of political implementability, it is hard to say how, even in abstract theory, these two instruments should be designed.
Let’s start with the negative externality that arises from the IRS facing high auditing costs due to complexity or opacity or whatever one might choose to call it. At present, if the IRS isn’t auditing anyone properly, the cost being incurred is zero! So there is no harm of this kind being inflicted – instead, the problem is underenforcement.
The paper could be a lot clearer on this issue, and I’m hoping that by the time it’s published it will be. BUT, I think the idea here is to determine how much the IRS ought to spend on the audit if it is making optimal choices based on the likely $$ return on auditing plus everything else that ought to guide such choices (e.g., knock-over effects on how equally different business sectors are being taxed).
This might lead to the retort: If the IRS doesn’t actually do the audit, isn’t that like taxing a factory for smoke it DIDN’T emit? But I think the answer, although not at present entirely clear on the face of the paper, is as follows: If the firm doesn’t emit smoke, there’s no social harm. But if the IRS doesn’t audit, there is social harm, albeit from the under-enforcement rather than the use and consumption of audit resources. Given that these audits should have been done, the social harm must at least equal that the amount that the auditing would have cost. Therefore, charging a Pigovian tax for the audit costs that should have been incurred but wasn’t does indeed get at a lower-bound measure of social harm.
The second instrument, which is the Bentham-Becker penalty upgrade for the
In the end, it’s hard to know – and, in many respects, a wholly separate type of problem about political feasibility and the like – how much we can really hope to get out of these two proposed instruments in practice. But it’s helpful to have them identified theoretically as getting at a pair of distinct though interrelated problems, i.e., under-taxation of the “complex” sector, along with higher enforcement costs that may be borne by the general citizenry.
One last point, consistent with the paper’s analysis but not much explored by it at this stage, is how interrelated the two instruments would be in practice. E.g., the more the IRS audits, the more the $$ it is actually spending on audits but the higher the probability of detection. There presumably would be multiple equilibria, in which the two instruments are set at different levels in order to get to some version of the same place. And a true optimization exercise, however unlikely in actual practice, would involve setting them jointly.
Source: http://danshaviro.blogspot.com/2026/11/nyu-tax-policy-colloquium-michael-loves.html
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
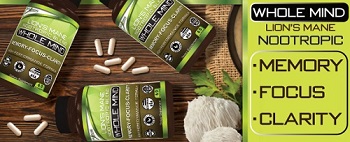
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,838,443,129 |
| Stories: | 8,737,178 |
Whistler Blowers, Insiders

