Debt Window Slams Shut: Meta Taps Shareholders For Up To $95 Billion, With Its Own Chip Suppliers Buying In
We warned that Zuck would have to come to shareholders with his hand out. This morning, he did.
Meta announced a gargantuan financing plan of up to $95 billion in new equity on Monday, topping even Alphabet’s upsized $84.75 billion equity raise from June. Our reaction, roughly 60 seconds after the headline hit:
There it is META TO OFFER $22.5B OF CLASS A COMMON STOCK
— zerohedge (@zerohedge) October 26, 2026
“There it is” because we had flagged it a week ago: regular readers will recall that ahead of Meta’s earnings (which the company moved up a full week for no obvious reason), we highlighted a question UBS asked out loud while everyone else was asking it quietly:
“Meta reports a week earlier than normal – trying to get ahead of the (cap raise) crowd?” – UBS
— zerohedge (@zerohedge) October 18, 2026
Well, the answer was yes. And just as important as the raise itself is what Meta is not doing: selling a jumbo bond. Coming the morning after Elon Musk said that debt markets have “almost entirely shut off access to money” for anyone without substantial non-AI revenue, Meta’s decision to fund itself with stock confirms what we have been saying for weeks: the AI debt pipeline has seized up, and even the strongest borrowers in the space would rather dilute shareholders than test it.
$22.5 Billion Now, $12.5 Billion In Converts, $60 Billion Later
Here is what Meta is selling, per its free writing prospectus and the 424B5 prospectus supplement filed this morning:
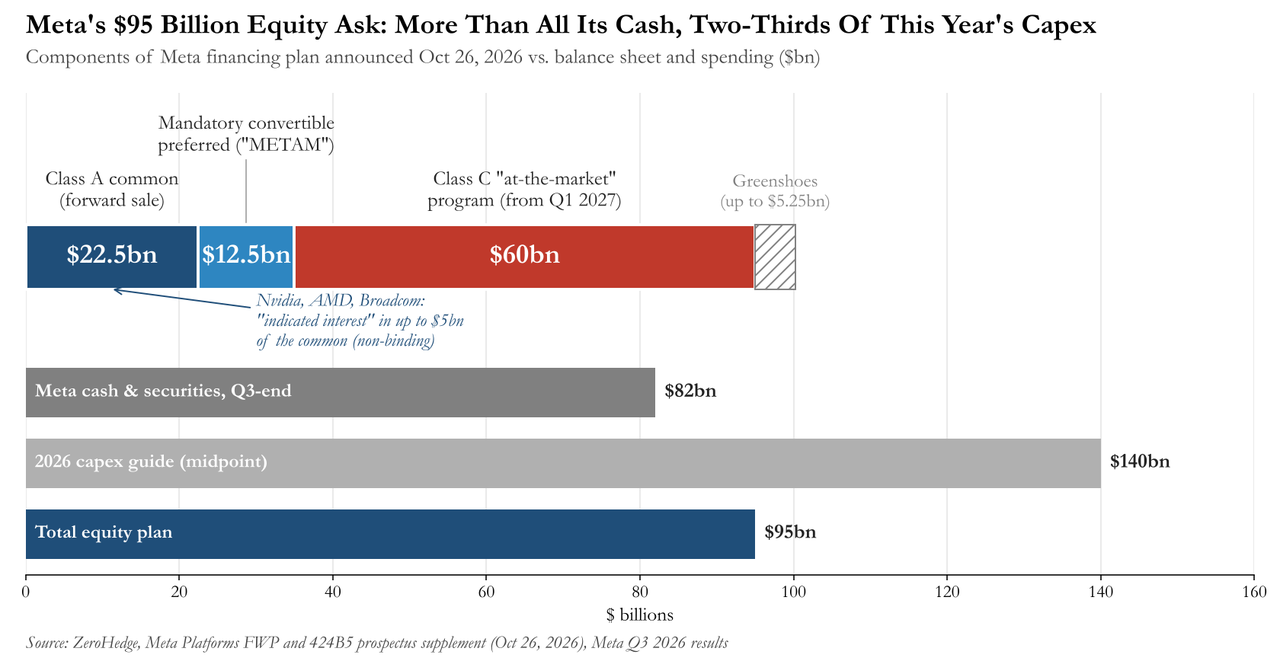
- $22.5 billion of Class A common stock, sold through forward sale agreements with Morgan Stanley and Goldman (plus a $3.375 billion greenshoe). Meta gets no cash up front, and can settle any time on or before November 19, 2027, in Class A or the new non-voting Class C shares.
- $12.5 billion of mandatory convertible preferred: 250 million depositary shares, each a 1/20th interest in a $1,000 preferred share, converting into common around August 15, 2029 and listing under “METAM” (with another 37.5 million depositary shares in the greenshoe).
- A $60 billion “at-the-market” program of non-voting Class C shares, to start in Q1 2027 once the Class C stock begins trading (the new share class becomes effective January 19).
Goldman’s offering snapshot shows the common deal pricing after the close today (October 26), with MS and GS as active bookrunners:
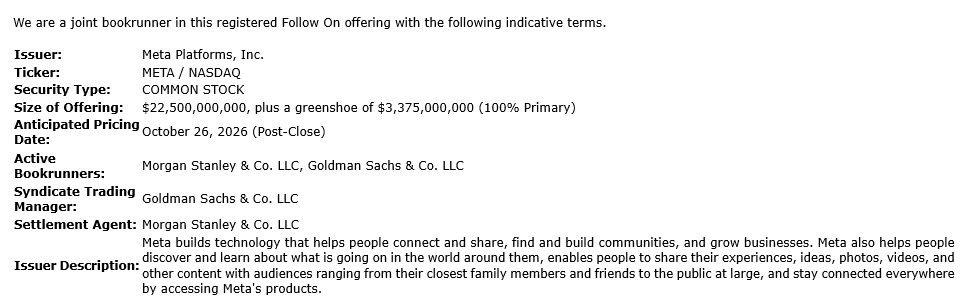
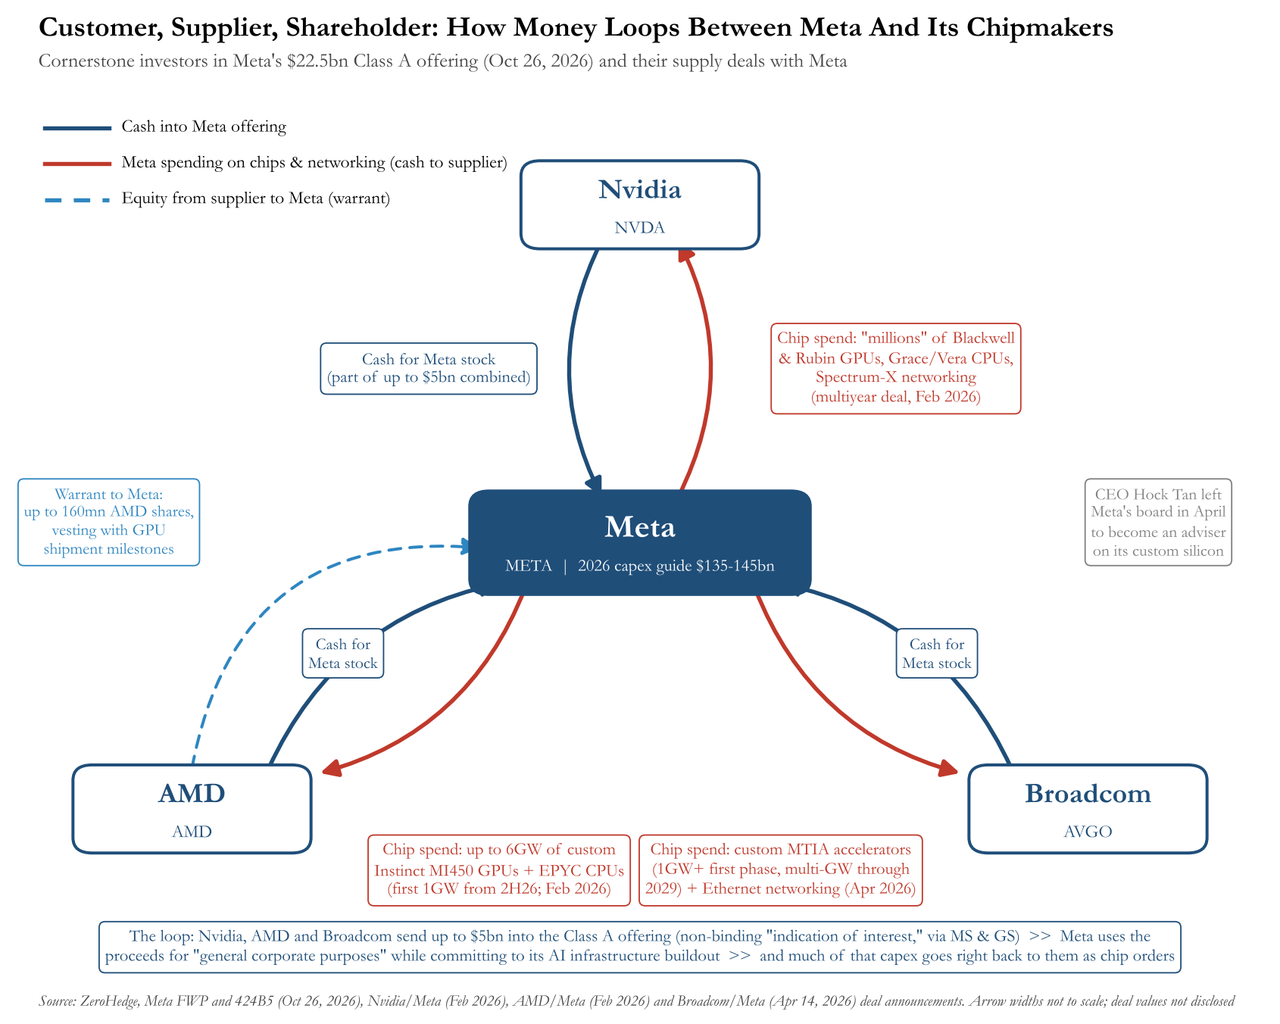
Then there is the cherry on top: Nvidia, AMD and Broadcom, three of Meta’s biggest chip suppliers, “indicated an interest” in buying up to $5 billion of the common stock at the offering price. That indication is non-binding, as the prospectus is careful to note: any of them “may determine to purchase more, fewer, or no shares.” More on that below.
We ran the numbers. At Friday’s $642.62 close, the $22.5 billion forward alone is about 35 million new shares (the prospectus has Class A outstanding rising from 2.214 billion to 2.249 billion). Do the whole $95 billion at that price and it comes to nearly 150 million shares, or roughly 6.7% of the Class A count (approximate, before greenshoes, and the converts’ share count depends on the price in 2029). And for the company that spent well over $100 billion buying back its own stock between 2021 and 2024, the converts come with a twist: per the prospectus, unless the preferred dividends are paid in full, “no dividends may be declared or paid on our Class A Common Stock… and we may not repurchase our Class A Common Stock.” Buybacks, meet dilution.
Here is how the ask stacks up against Meta’s $82 billion of cash and securities, and the $140 billion midpoint of its 2026 capex guide:
Meta’s pitch for the deal reads like a product launch. “AI is creating significant opportunities for Meta across its core business,” the company said, and its “AI investments are already generating tangible returns through increased engagement, improved advertising performance and increased monetization.” It also says it will fund itself through “a balanced mix of operating cash flow, investment-grade debt, strategic partnerships, and equity capital,” adding that its “Aa3/AA- credit ratings allow it to raise long-term debt efficiently.”
Which is a curious thing to say, maybe, a week after Meta’s own Schedule 14C admitted the exact opposite: the special committee “recognized that debt financing alternatives of the magnitude that Company management was considering could have an adverse effect on the Company’s credit ratings.” Translation: the bond market can’t absorb what Meta needs without the ratings taking a hit, so shareholders get the bill.
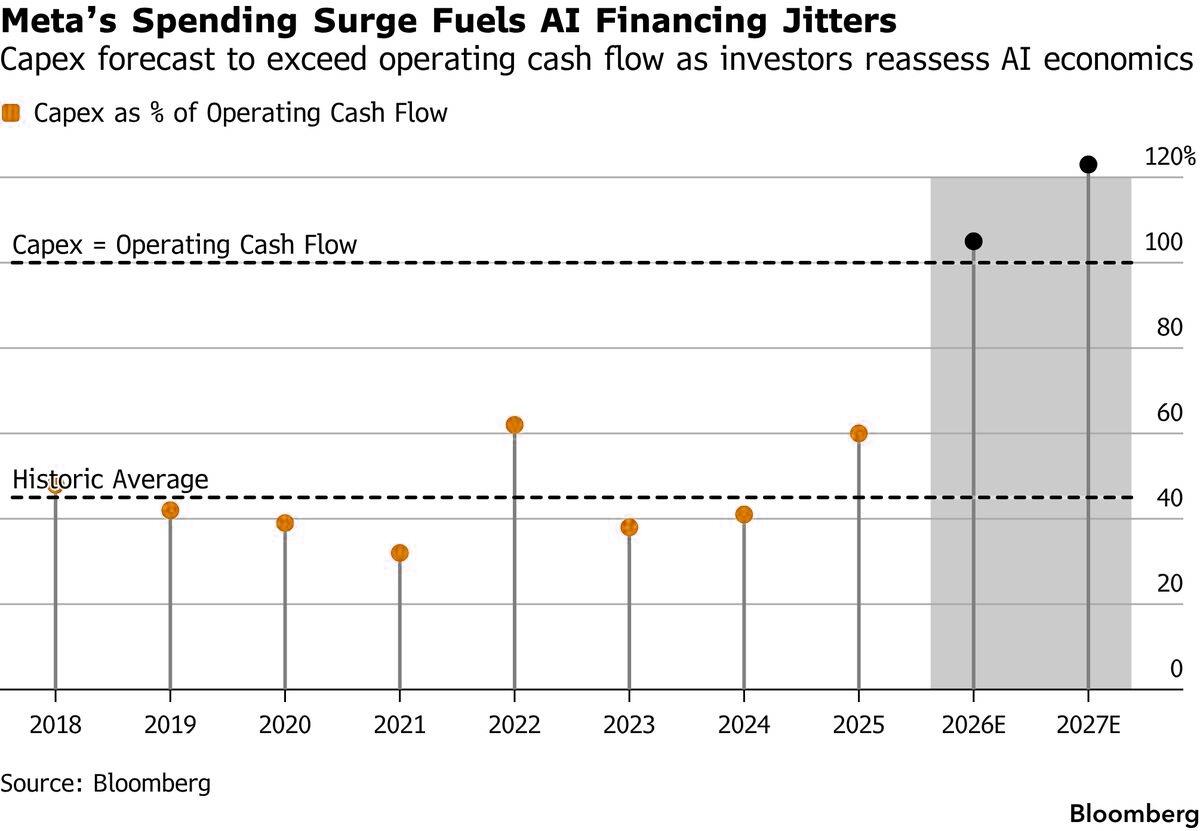
The math behind it hasn’t changed since last week. As Bloomberg showed this morning, Meta’s capex is set to exceed its operating cash flow this year (for the first time in at least eight years), and hit roughly 120% of it in 2027:
Shares, incidentally, pared initial losses to trade up 1.6% at $654 in the premarket, according to Bloomberg, after tumbling last Thursday. Nothing says “relief” like 150 million new shares.
“Massive Capital Raises Incoming”
None of this should surprise anyone who read us last week. In “Please Don’t Stop The Museic” (Oct 21) we quoted JPMorgan’s TMT desk, which had found that most of the buyside was already braced for a raise:
JPM on META equity offering: “a majority of investors still believe that an Equity Raise is likely post-Q3… We all know that META is going to burn FCF next year; the only question is whether the cost of debt or the cost of equity will be lower when they need to raise capital.”
— zerohedge (@zerohedge) October 21, 2026
Then came the print. Meta tightened its 2026 capex guide to $135-145 billion, joined Amazon in the negative free cash flow club, and filed a 14C showing management had told the board it needed to raise “hundreds of billions of dollars over a period of several years beginning as early as fall 2026.” Meta’s CDS blew out to a record, as we detailed in “Meta Plunges, CDS Hits Record As Barclays Spots ‘Massive Spending’ Warning In The Fine Print.” And when the market spent the day fixating on the capex number, we pointed at the bigger one:
Also, market is forgetting that while Meta will spend $250BN in 2027 capex, it also has to spend $210-225BN in 2027 opex to fund off balance sheet liabilities. -> Massive capital raises incoming https://t.co/SlwL4VOvfd
— zerohedge (@zerohedge) October 22, 2026
Four days later, here they are.
What the sellside got wrong was the timing. The consensus last week was that nothing would happen until the Class C shares started trading: JPMorgan’s TMT trader Mark Schilsky titled his first take “C You in January,” arguing “we won’t get one until early 2027. The overhang lives on!” Barclays’ Andrew Keches, meanwhile, figured equity was “unlikely before then” and expected a bond deal before year-end, maybe the “standard” $25 billion, maybe “a $50bn-plus trade.” Instead, Meta structured around the January date with a forward sale it can settle in either share class, and skipped the jumbo bond altogether (for now).
Recall the 14C’s other key line: “timing is important to secure capital before competitors saturate various funding options.” Meta just went first.
Musk: Debt Markets Have “Almost Entirely Shut”
Why stock instead of bonds? Elon Musk, whose SpaceX just closed $40 billion of GPU debt, explained it on Sunday afternoon, replying to Chamath Palihapitiya’s thread on neoclouds and data center land:
Pretty much. As of the past few weeks, debt markets have almost entirely shut off access to money for any company that doesn’t have substantial revenue independent of AI data centers. SpaceX closed $40B of debt for GPUs, but we’re investment grade and have Starlink & launch revenue. That means the 200+ neoclouds are going to see guppy-level death and consolidation. Some will make it through, but not many.
— Elon Musk (@elonmusk) October 25, 2026
“Guppy-level death” is a new one, though the message will be familiar. Goldman’s TMT desk led its Monday note (available to pro subs) with exactly this: “focus continues to be on AI Capital raising (which has become a bigger and bigger talking point in recent weeks, given the well-documented capital needs of the industry + stress in bond/convert market).” CoreWeave was down 5% in the premarket on Musk’s comments.
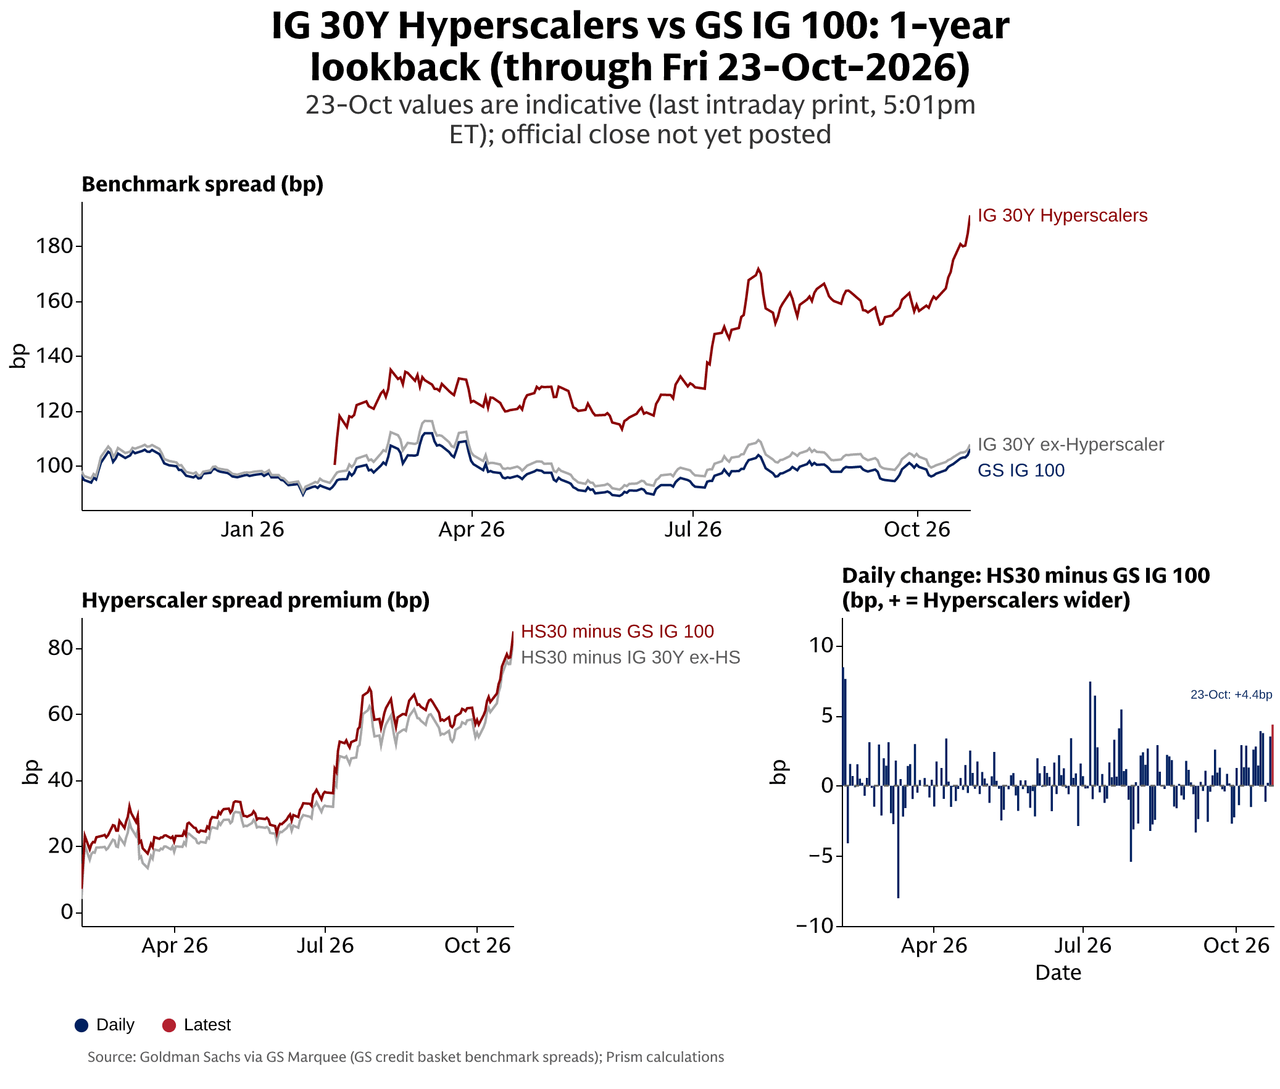
The stress is visible across the AI credit stack. In his weekend wrap, “IG Credit Week in Review” (available to pro subs), Goldman IG trader Brad Shelofsky writes that last week was shaped by “a significant re-rating of AI risk as markets reassessed the feasibility of funding the buildout.” While the prior week’s pain was in the neoclouds, “this week the Hyperscalers shouldered a greater share of the blame”: Goldman’s IG hyperscaler basket closed 17bps wider, “its worst week on record outside of the similar moves in July,” and its 30-year hyperscaler basket hit new wides, now 85bps cheap to the IG100 ex-hyperscalers, and 90bps cheaper than when it launched in February:
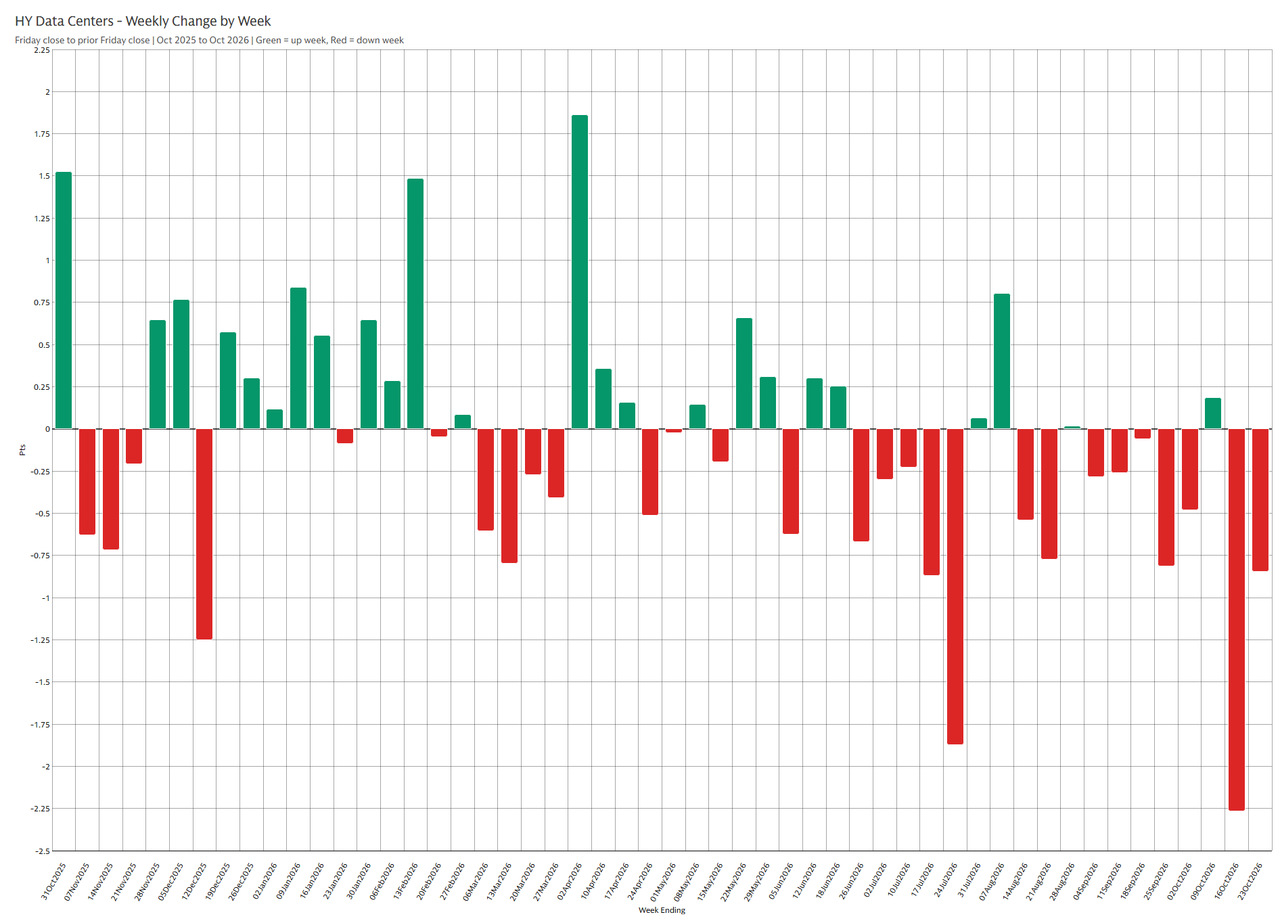
The HY data center basket fell another 0.95 points on the week (chart source GS FICC), its seventh down week in the past eight:
Shelofsky also quotes Jensen Huang, who said there’s “a scarcity of capital. The demand of the capital is much greater than the availability of the capital. That’s going to get solved.” (We have a guess how.) And he admits something few traders put in writing:
“I’ll start by saying that conviction is rather low here and I don’t feel as if that is unique. I fell into the mean reversion trap too early, believing a META deal would create a runway for a Q4 bounce in a beaten-up and optically cheap space but the concerns around funding pressures only grew this week. I still believe you will see a squeeze at some point in Q4 like the move we witnessed in July, however, that can’t happen until the Meta and SpaceX Chip deals are cleared… The key headwinds remain weak sentiment and a lack of willingness from Real Money investors to take risk higher until there is greater clarity on when the rate of supply growth stops being exponential.”
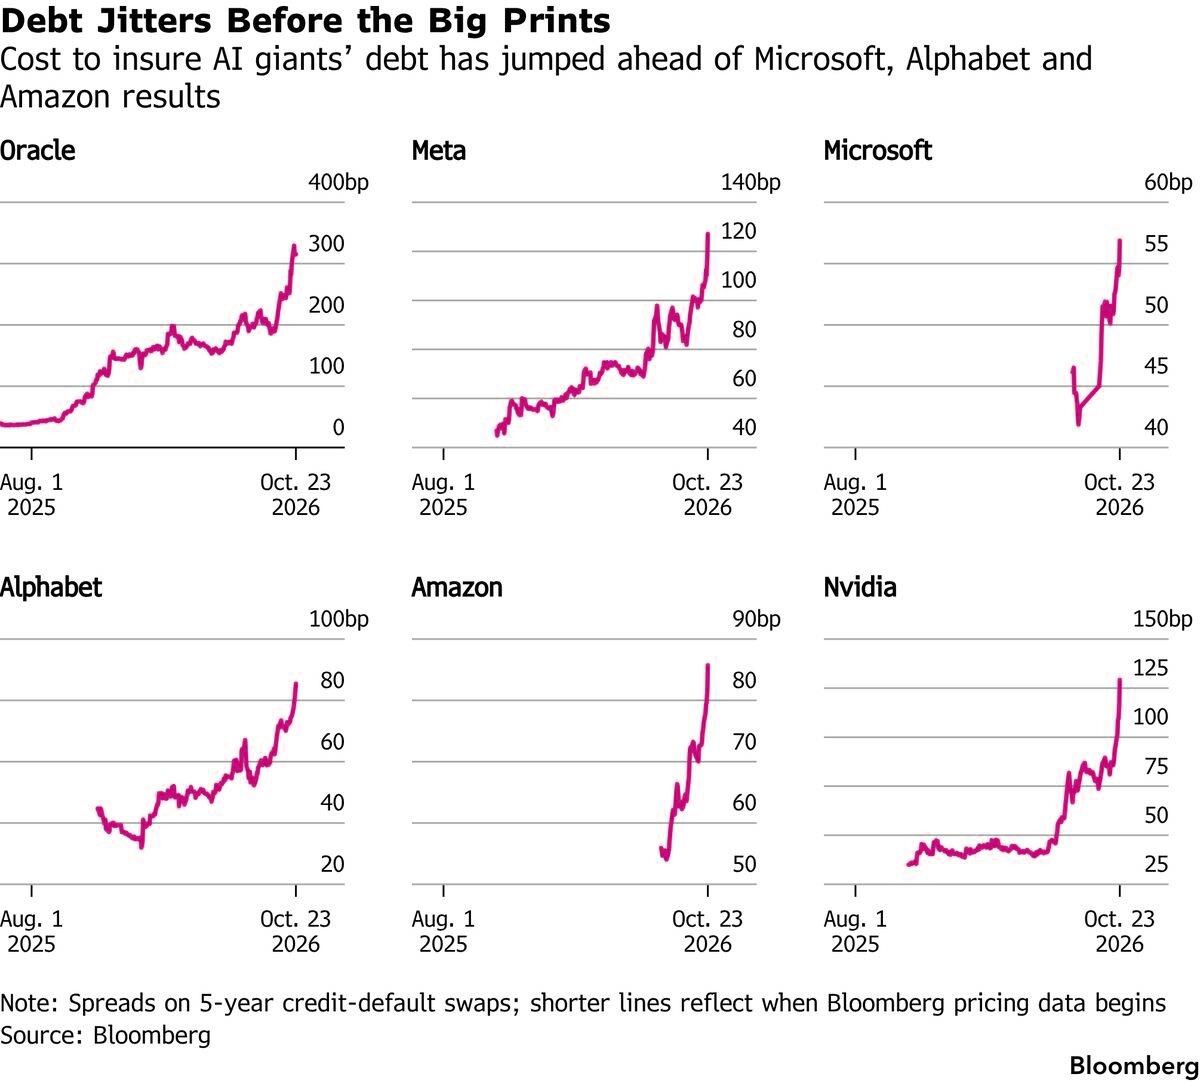
In other words, the IG desk was waiting for a Meta bond deal to clear the air. It got a stock deal, which leaves the bond question open. Meanwhile, the cost of insuring AI giants’ debt has gone vertical ahead of this week’s prints (chart via Bloomberg):
“Without Debt, There Is No EPS Growth”
We have been tracking the drought for weeks. On October 13, in “‘Until The AI CapEx Debt Creation Machine Turns Back On’: Goldman Says Credit Is Calm… For About Two More Months,” we explained why credit had stayed calm (the one borrower big enough to break it had stopped borrowing), and why that wouldn’t last:
Just how full is the hyperscaler/AI IG debt pipeline: there have been zero deals since the start of September. And SPVs not doing better. As a reminder, debt becomes capex, becomes revenue, becomes EPS. Without debt, there is no EPS growth.
— zerohedge (@zerohedge) October 13, 2026
On Friday, Morgan Stanley’s credit strategists called it “The State of AI Financing: A Pause, Not a Pullback” (also available to pro subs), tallying just ~$23 billion of AI-related supply globally in September and zero in US IG. As we wrote in “Pause Or Wall?” on Saturday, we had a different word for it: a wall. Two days later, the biggest spender of them all routed around it with stock.
That matters because the entire AI capex forecast rests on a debt pipeline that has to get much bigger. Goldman’s chief credit strategist Amanda Lynam expects $420 billion of IG issuance from the hyperscalers alone in 2027 (full note available here to pro subs), versus about $230 billion in the record year to mid-September:
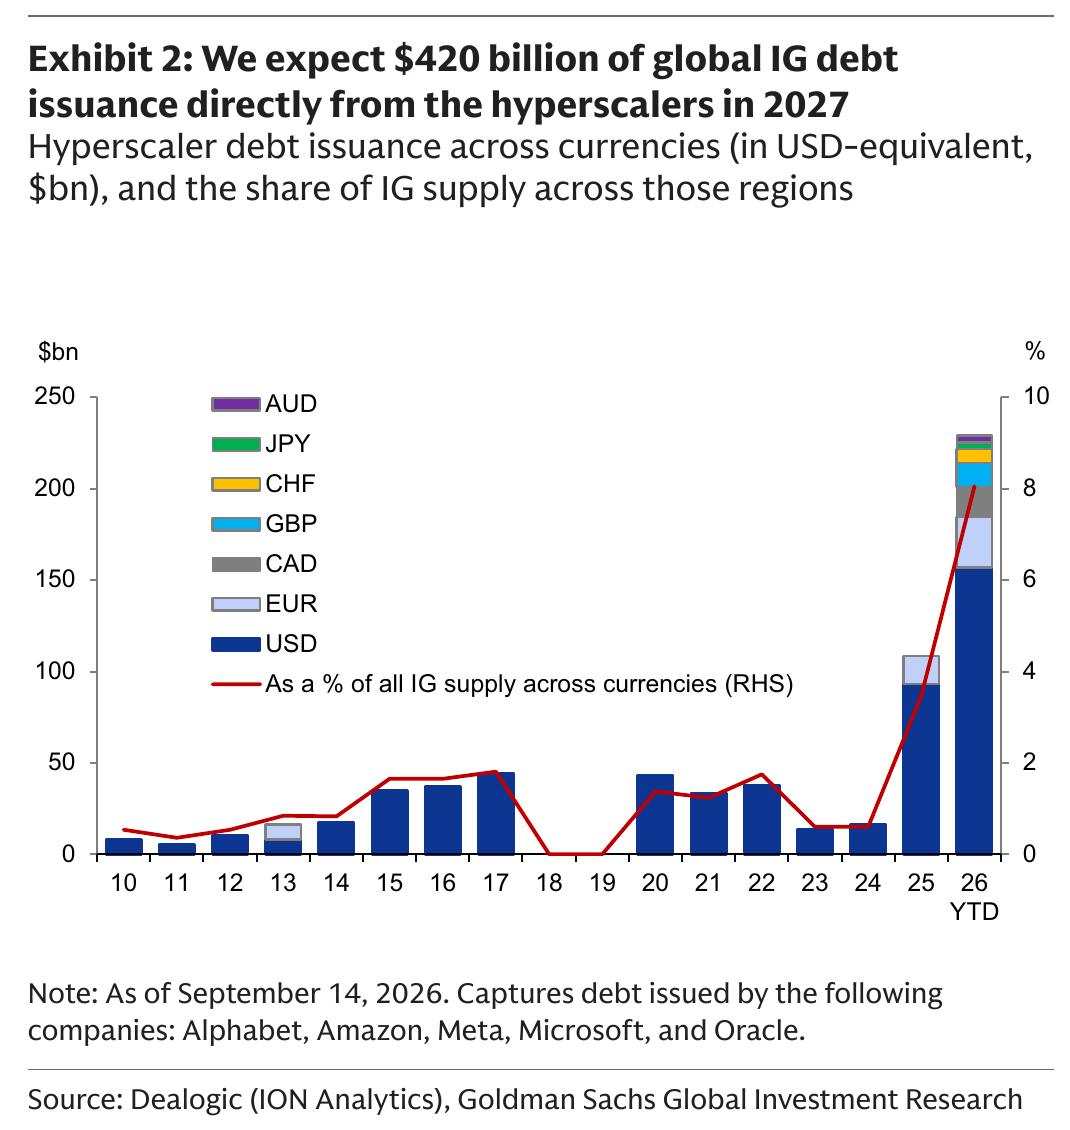
Lynam’s latest comments, relayed by Goldman’s TMT specialists this morning, explain why the plumbing is creaking. In the AI buildout, “the key focus is no longer just the cost of capital, but its availability and strategic value.” Off-balance sheet leases and purchase commitments across five leading hyperscalers now total $2.8 trillion, an eightfold increase since 2023 (our own count, including Nvidia, Broadcom and SpaceX, hit $3.6 trillion last week), and the rating agencies can’t agree on how to treat them: S&P adjusts leverage for off-balance sheet leases, Moody’s and Fitch don’t, so “potential methodology changes are therefore worth watching.” Most telling, she flags that “some companies are explicitly acknowledging the need to secure capital before markets become saturated – a new development that highlights the distinctive nature of the AI financing cycle.” That would be Meta’s 14C, word for word.
Put differently, when an Aa3/AA- issuer with $97 billion in operating cash flow through nine months decides equity is the better deal, the debt market has a pricing problem, a capacity problem, or both.
Vendor Financing, Now In Equity Form
Which brings us back to the cornerstone investors. Nvidia, AMD and Broadcom will (maybe) buy up to $5 billion of Meta’s stock, so that Meta can keep buying Nvidia, AMD and Broadcom chips. We have written plenty about AI circularity over the past year, from GPU-backed SPVs to chipmakers financing their own customers, but seeing three suppliers anchor a customer’s equity offering is a new rung on the ladder. And the relationships run deeper than a one-off ticket. In February, Meta signed a multiyear deal for “millions” of Nvidia Blackwell and Rubin GPUs plus Grace and Vera CPUs, and a separate pact for up to 6GW of custom AMD Instinct GPUs, under which AMD handed Meta a warrant for up to 160 million AMD shares, vesting as the chips ship. In April, Broadcom extended its custom MTIA accelerator partnership with Meta through 2029, while its CEO Hock Tan left Meta’s board to become an adviser on, naturally, its custom silicon. So AMD gives Meta equity to buy its chips, Meta (maybe) sells equity to AMD to help pay for them, and everyone books revenue. Here is who pays whom:
And it presumably helps fill a book that, at $35 billion underwritten, is no small ask on a Monday morning before Microsoft, Alphabet and Amazon report.
For balance, not everyone sees a crisis. JPMorgan’s Market Intelligence desk, relaying a FICC financing call in this morning’s briefing (available to pro subs), says “Credit markets are becoming more discriminating on AI Infra, but there’s nothing to suggest a broader funding crisis.” AI infrastructure has absorbed more than $500 billion of debt this year (over $350 billion in IG, over $60 billion in leveraged finance, plus structured and private credit, the latter $100 billion-plus by JPM’s “best guess”), and while “all-in funding costs for hyperscalers maybe have increased ~120bps,” the bank says the ecosystem “remains functional.” Fair enough. But the same note concedes that “Equity % will also need to move up as volumes get up to 20GW+,” and that banks have “become more selective about underwriting terms.” Today, Meta showed what that looks like in practice.
First Meta, Then Who?
If Meta, with an AA- rating and one of the world’s two biggest ad businesses, prefers stock to bonds, the question for everyone else is obvious. Oracle hosts its investor day on Wednesday. SpaceX still has to price its $40 billion chip deal. Microsoft and Alphabet report Wednesday, Amazon on Thursday, and Goldman’s TMT desk warns that “any signs of further equity issuance or balance-sheet pressure are unlikely to be well received.” As for the neoclouds, which have neither Starlink nor Instagram to fall back on, Musk has already written the obituary.
Good for META. Now let’s see everyone else’s equity offering https://t.co/l0ve6NNBVl
— zerohedge (@zerohedge) October 26, 2026
The bulls will say the debt drought is temporary, that the “machine” turns back on once earnings clear, and that Meta just pre-funded itself cheaply at a share price 17% below its September high. Maybe. We think the more likely read is the simpler one: the cheapest money in the AI trade has already been borrowed, the next $420 billion of bonds will cost a lot more than the last batch, and the companies that can still sell stock will sell it while they can. The 14C told us as much: Meta wanted to raise capital “before competitors saturate various funding options.” When the strongest balance sheet in the group is racing for the exit door of the capital markets, it’s worth asking what it knows that the price targets don’t.
For shareholders, the trade-off is now explicit: years of buybacks just went into reverse, and the dilution has only started. The ATM alone is $60 billion, and as the 14C made clear, that’s still nowhere near “hundreds of billions.”
Much more in the full Goldman “IG Credit Week in Review,” the Morgan Stanley “State of AI Financing“, the JPM “Market Intel” notes, all available to pro subs.
Tyler Durden Mon, 10/26/2026 – 09:12
Source: https://freedombunker.com/2026/10/26/debt-window-slams-shut-meta-taps-shareholders-for-up-to-95-billion-with-its-own-chip-suppliers-buying-in/
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,836,094,111 |
| Stories: | 8,726,857 |
Whistler Blowers, Insiders

