Dowd: “Investment Bubbles Are A Feature Of Capitalism, Not A Bug”
Authored by Ed Dowd via Ed Dowd’s Beyond The Narrative Substack,
On Friday October 9th Bloomberg published an article titled “Jeffries’ Chris Wood Sees ‘Massive Capital Destruction’ in AI.” His view is that the most likely long-term outcome of the AI boom is massive capital destruction in the US, with market share shifting to cheaper open-source Chinese models. Wood has mostly got it right in my opinion except for two differences. My first difference is that Chinese models are not the only open-source models available and that western open-source models are closing the gap. Secondly, while his view correctly flags the overbuild and the competitive pressure from lower-cost alternatives what it leaves out is the long history of innovative technology infrastructure bubbles and the reliable pattern that follows them which is:
excitement/mania → overinvestment → financial collapse → distressed assets → recapitalized cheap infrastructure fuels the next economic wave.
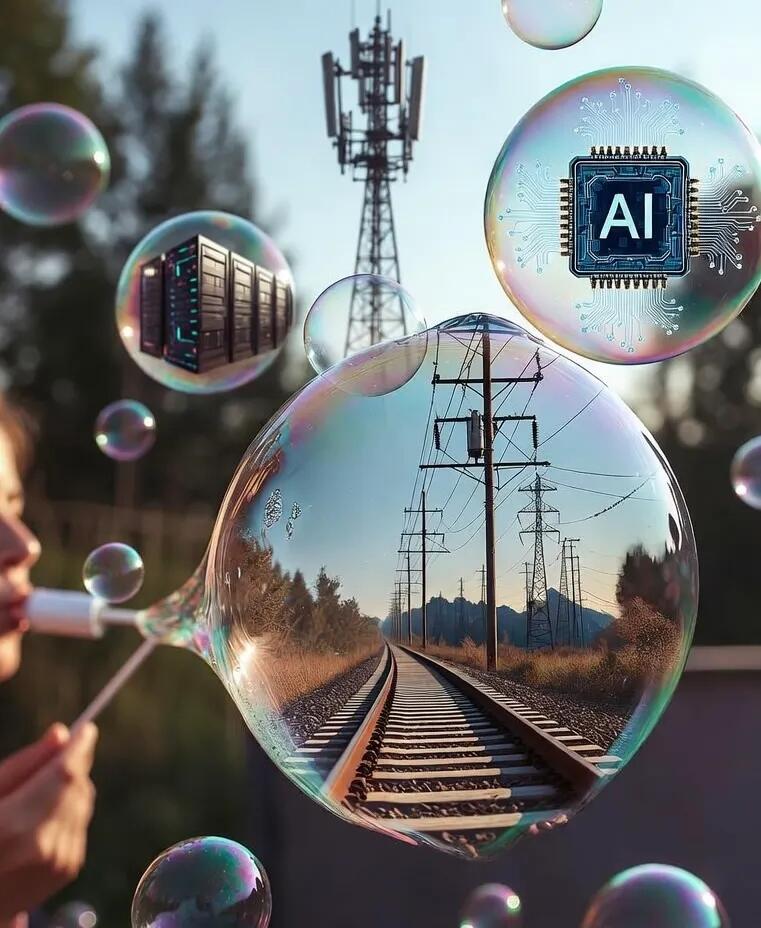
In regard to the AI bubble, I believe we are currently in the overinvestment phase with cracks emerging. Let us look at some historical examples to illustrate the pattern and see if we can glean what the future of this current bubble might look like.
The US Railroad Bubble
In the decades after the Civil War, railroads became the transformative technology of the era. Capital, much of it European, flooded in. Between the late 1860s and early 1870s, tens of thousands of miles of track were laid, often into sparsely settled or unprofitable territory. Speculative financing, land grants, and the expectation of endless growth created a classic mania. Early projects showed strong returns, which attracted more money into later, riskier lines built far ahead of demand. When financing dried up, highlighted by the failure of Jay Cooke’s bank in marketing Northern Pacific bonds, the Panic of 1873 followed. More than 100 railroads went bankrupt in the ensuing years, banks failed, and investors were wiped out. The depression lasted years. Yet the physical tracks remained. The surviving and reorganized network became the backbone of American industrial expansion, enabling efficient movement of goods, people, and capital that powered decades of growth. The overbuilt infrastructure, once distressed and recapitalized, proved far more valuable to the broader economy than the paper losses suggested.
The 1920s Utility Bubble
The 1920s electrification boom followed a similar script. Central-station utilities expanded rapidly, and holding companies consolidated regional systems into large, leveraged empires. Electricity generation and revenues grew dramatically as the technology moved from novelty to infrastructure. Utility stocks soared and became a major part of the market. Holding companies facilitated access to capital and technical expertise, but the structures were opaque, and capacity was built aggressively. The 1929 crash and subsequent Depression exposed the leverage and accounting. Samuel Insull’s empire collapsed in spectacular fashion, and the Dow Jones Utilities Average plunged. Reforms including the Public Utility Holding Company Act of 1935 broke up the largest structures and shifted the industry toward regulated regional monopolies. What remained was a vastly expanded electrical grid and generation capacity. Widespread electrification transformed industry, homes, and productivity for the rest of the century. The bust was painful for equity and debt holders; the long-term economic payoff from cheap, abundant power was enormous.
The Dotcom Bubble
The most recent and directly analogous example is the late 1990s telecom fiber buildout during the Dotcom era. Carriers and infrastructure firms poured hundreds of billions into fiber-optic networks, switches, and related equipment, largely financed with debt and encouraged by forecasts of internet traffic doubling every few months. Capacity vastly exceeded near-term demand. After the bubble burst, market values collapsed, many telecoms went bankrupt, and bandwidth prices fell sharply. A large portion of the newly laid fiber sat “dark” or unlit. Through bankruptcies and recapitalizations, that physical infrastructure was acquired at deep discounts, often pennies on the dollar. The resulting cheap broadband made business models viable that would have been prohibitively expensive otherwise. Google, YouTube, Facebook, Apple’s smartphone ecosystem, Netflix, software-as-a-service, and cloud services all scaled on that excess capacity. Without the overbuilding and subsequent distress, Web 2.0 as we know it does not happen at the same speed or cost. The capital destruction was real but the residual infrastructure seeded the next wave of growth.
AI Bubble (Yes it is a bubble!)
I believe we are now in the AI infrastructure equivalent of the overinvestment phase. Massive capital is flowing into data centers, chips, power, and related equipment. The sheer scale of spending is turning advanced AI models into a commodity faster than many equity and debt investors appear to appreciate. Chinese open-source models are already applying downward pricing pressure, consistent with the Jefferies view. Cracks are visible. In my Substack piece “Wall Street’s AI Capex Party…It’s 2 AM & The Bar Is About to Close!”, the signals included stalled private credit funding for the buildout, cracking enterprise demand as promised productivity gains fail to materialize at scale, looming power constraints that are becoming the binding limit rather than chip supply, and open-source pricing pressure that compresses margins.
Additional recent indicators from public commentary reinforce this: circular deals in which AI companies run negative free cash flow and rely on debt investors to keep purchasing chips at elevated prices; recent analyses showing major players cannot cover contracted compute commitments under realistic revenue assumptions; and narrative shifts such as space based data centers that paper over terrestrial grid and power bottlenecks. Growth rates implied by current valuations look vulnerable once the second derivative of funding and utilization slows. It is not a question of not if the bubble bursts but when it bursts.
Credit Markets Always End Infrastructure Buildouts
Debt and credit have been central to every one of these infrastructure buildouts. In the railroad boom, bonds financed the majority of the expansion, often more than three-quarters of the capital. When those markets stopped absorbing new bond issues (e.g. Jay Cooke & Co. could no longer place Northern Pacific bonds) the credit system seized up. Then bank runs followed, the New York Stock Exchange closed for ten days, and within two years roughly a third of outstanding railroad bonds had stopped paying interest. The equity markets lagged in this period…credit markets ended the railroad party abruptly.
The 1920s utility expansion followed the same pattern on a different scale. Samuel Insull’s holding company pyramid relied on layers of debt and bank loans secured by the securities of the operating companies themselves (financial engineering). Once revenues softened and the banks refused to roll the notes in 1932, the structure collapsed into receivership. In this period the equity markets led the credit markets first with the 1929 crash then credit followed later.
In the telecom fiber boom, carriers raised hundreds of billions in bonds and used vendor financing and circular deals to keep the buildout going. Credit markets ultimately marked the end of the buildout but equities peaked in March of 2000 before credit. Credit spreads later widened sharply in 2001 and 2002, defaults clustered in the sector for years, and bondholders recovered roughly twenty cents on the dollar in many cases. When lenders stopped funding incremental capacity, the overinvestment phase ended and the financial collapse began.
The same dynamic is now visible in the AI buildout, where private credit has stalled, circular debt structures are proliferating, off balance sheet financing is growing and early signs of stress are appearing in CCC junk credit markets. Whether equity markets lead or lag this cycle remains to be seen but the case could be made that given the tremendous amount of passive equity investing the discounting mechanism of equity could lag and credit leads this time.
Bottom Line
Innovative technology capex cycles repeat themselves because human nature has not changed. Mania and excitement give way to overinvestment, which produces financial collapse and distressed assets. Those assets then become the cheap foundation for the next economic wave. Those who believe in cycles and a constant human nature may want to protect themselves accordingly and reduce exposure in the AI complex where risk-reward no longer makes sense. Then when the bust does arrive watch for the opportunities that emerge from the ashes where durable longer-term value will be created.
Bubbles are a feature of capitalism, not a bug. They destroy capital in the short run and, through the process of overbuilding and recapitalization, often leave behind the physical and technical foundation for longer-term productivity gains. The pattern is consistent throughout history…though the timing and severity may vary. The long-term outcome for the economy is usually more favorable than the peak-to-trough equity charts imply and a net positive over time.
“What has been will be again, what has been done will be done again; there is nothing new under the sun.” Ecclesiastes 1:9
Tyler Durden Wed, 10/14/2026 – 15:20
Source: https://freedombunker.com/2026/10/14/dowd-investment-bubbles-are-a-feature-of-capitalism-not-a-bug/
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
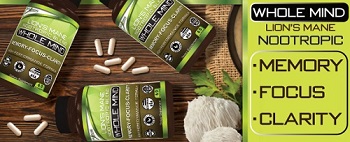
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,834,920,868 |
| Stories: | 8,720,769 |
Whistler Blowers, Insiders

