Futures Rise, Oil Slides As Iran’s Supreme Leader Talks Peace And Shrugs Off Ras Tanura Attack
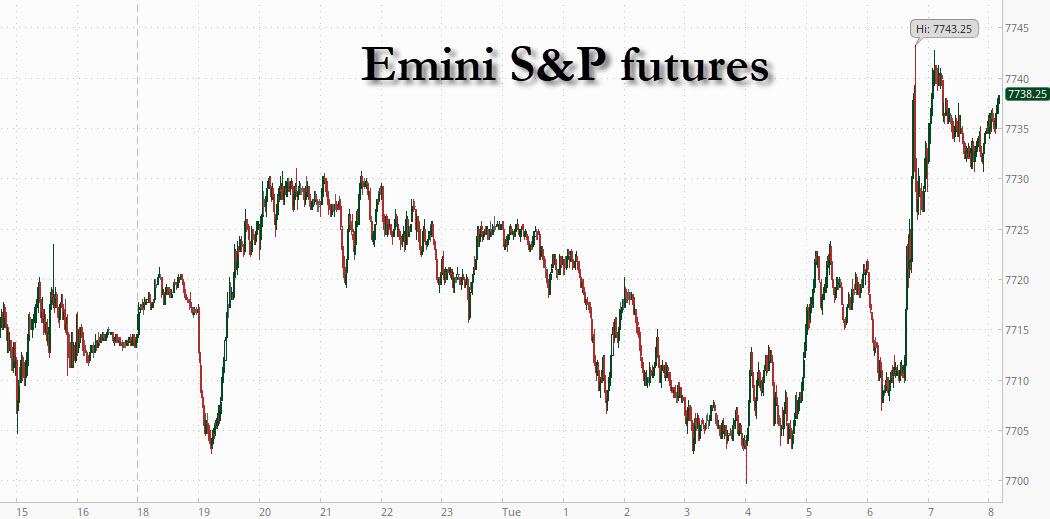
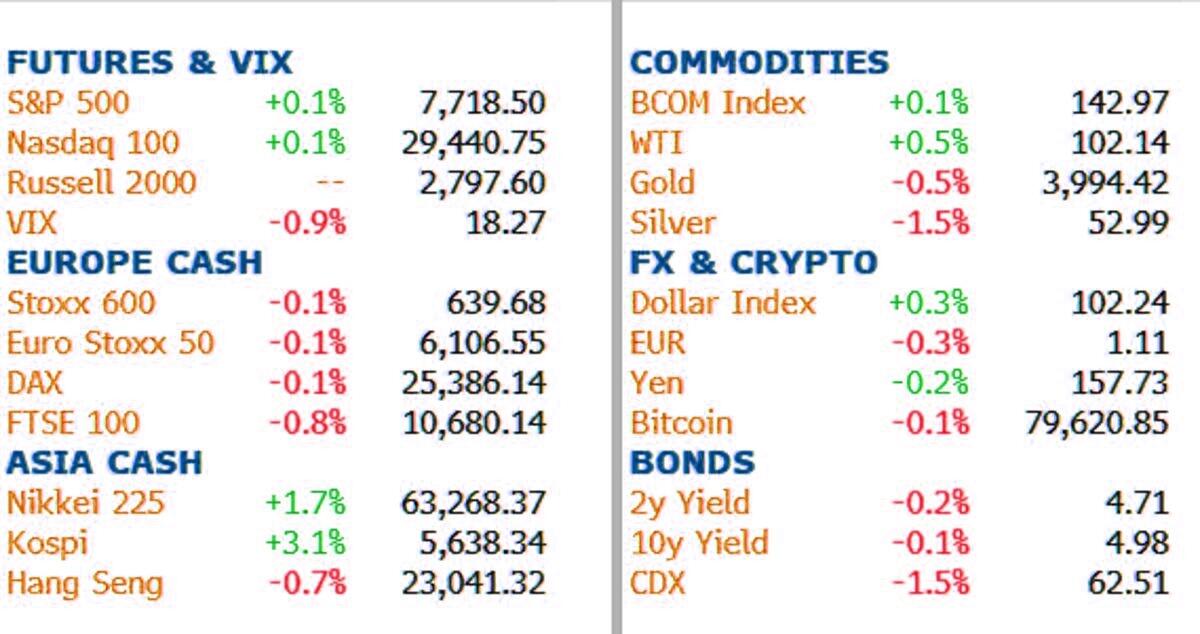
US futures are higher as hopes for a diplomatic end to the Iran war got a fresh boost after Monday’s Mecca Pact talks in Tehran, with Supreme Leader Mojtaba Khamenei calling for pursuing the conditions set out by Iranian officials to end the war and an Iranian ambassador floating a seven-day plan to reopen Hormuz, which more than offset a Houthi missile attack on Saudi Arabia’s Ras Tanura refinery; as a result oil slid and Treasuries rallied, with the 10Y yield slipping to 4.97% ahead of today’s $70BN 5Y auction. As of 8:15am ET, S&P futures are 0.4% higher while Nasdaq futures gain 0.7% and Dow futures rise 0.3%, having spent most of the overnight session flat as the Anthropic IPO euphoria which sparked Monday’s tech-led rally (S&P +0.70%, Nasdaq +0.82%) faded just as the bills for AI resume getting bigger: Meta upsized its equity raise to $25BN in common stock (part of a package of up to $97.5BN) while Broadcom arranged a $63BN deal to finance chips for Anthropic. In premarket trading, Tesla leads the Mag 7 while Microsoft lags; memory names are the standout (JPM’s DRAM basket +2.1%), Broadcom gains 2.4% on a D.A. Davidson upgrade tied to Anthropic, UPS rises 2% after raising guidance and Whirlpool slides 7.9% after its third guidance cut of the year. The day’s driver is Iran (again): oil, which jumped in early European trading on the Ras Tanura reports, reversed lower once the Khamenei headlines hit, with WTI down about 1% near session lows after trading in a $100.60-102.82 range. Treasuries are 2-3bps richer in the front end and belly, steepening the curve, while bunds and gilts outperform; French OATs underperform, with the OAT-Bund spread back above 160bps after French consumer confidence crashed to the lowest since 2013. The Bloomberg Dollar Spot index halved its earlier 0.2% gain as oil dropped, though EUR/USD still hit a two-week low around 1.1143. Gold is back below $4,000 (-0.5%), silver drops 1.5% and copper is up 0.9%; bitcoin slipped under $80,000. US economic data slate includes ADP weekly employment (8:15am), durable goods (8:30am), FHFA and Case-Shiller house prices (9am), Conference Board consumer confidence, Richmond Fed manufacturing and new home sales (10am) and Dallas Fed services (10:30am). The Fed is in its pre-FOMC blackout, so there are no Fed speakers; there are $54BN 52-week and $95BN 6-week bill sales at 11:30am and the $70BN 5Y note auction at 1pm.
In premarket trading, Tesla is leading gains among Magnificent Seven stocks as the electric-car maker is on track to outperform the cohort for a second consecutive session: Tesla (TSLA) +1.1%, Nvidia (NVDA) +0.6%, Alphabet (GOOGL) +0.4%, Amazon (AMZN) +0.3%, Apple (AAPL) -0.3%, Meta Platforms (META) -0.4%, Microsoft (MSFT) -0.6%
- Amkor Technology (AMKR) gains 3.7% after the semiconductor manufacturing company’s results were seen as positive on several metrics, including gross margins.
- Broadcom Inc. (AVGO) rises 2.4% after D.A. Davidson upgraded the chipmaker to buy from neutral, seeing potential upside related to Anthropic.
- Cadence Design Systems (CDNS) is up 2.1% after the maker of electronic design automation software raised its full-year forecast and reported third-quarter results that beat expectations.
- Hilton Worldwide (HLT) falls 4.8% after the hotel operator gave a forecast for adjusted earnings per share for the fourth quarter that fell short of the average analyst estimate.
- JetBlue (JBLU) rallies 7.2% after the carrier reiterated its expectation to deliver at least $1 in earnings per share and positive free cash flow in 2028. The shares closed Monday at a record low as the airline grapples with cash burn and elevated oil prices.
- MidCap Financial Investment (MFIC) jumps 20% after Ares Capital agreed to acquire it in a stock-and-cash deal with total enterprise value of ~$2.6b, paying $10.88 per fully diluted MFIC share. Ares Capital (ARCC) falls 1.9%.
- Moderna (MRNA) falls 3.2% after William Blair downgraded the drugmaker to market perform from outperform, citing valuation concerns, following a run-up in the stock.
- UPS (UPS) gains 2% after the courier raised its financial guidance for the year, suggesting it expects to benefit from high prices and resilient demand through the holiday season.
- Whirlpool Corp. (WHR) slides 7.9% after the appliance maker cut its revenue forecast for the full year to below Wall Street’s consensus.
In other corporate news, the AI funding frenzy rolls on: Meta upsized its common stock offering to $25 billion from $22.5 billion, with Nvidia planning a $3 billion investment in the raise (because nothing says organic demand like your chip supplier buying your stock, as we discussed yesterday), while Broadcom arranged a $63 billion deal to finance the purchase of chips for Anthropic and Goldman and Morgan Stanley scored the top roles on Anthropic’s upcoming IPO. PIMCO bought a $4 billion slice of a huge SpaceX financing deal, Microsoft is offering buyouts to about 60,000 workers (as reported yesterday) and BNY Mellon said it is stepping up efforts to monitor AI token costs. Elsewhere, Universal Music discussed going private with buyout firms, Ares Capital is buying MidCap Financial, La Caisse is buying a stake in BCE’s tower unit for C$2.45 billion and Investcorp is buying into a Saudi fire-safety firm. On the earnings front, Coca-Cola posted comparable EPS of 91c vs. 88c expected, PayPal raised its FY adjusted EPS forecast to about $5.60 from about $5.38, Boeing’s adjusted free cash flow of $464 million topped the $325.1 million estimate, and UPS beat with adjusted EPS of $1.69.
Monday’s jolt higher in tech stocks after Anthropic’s IPO filing is having limited follow-through, with investors once again questioning the sustainability of AI demand just as companies issue ever-bigger bills to fund it. The SOX has suffered a peak-to-trough drawdown of more than 25% relative to the S&P 500 this year, rivaling some of the worst selloffs in recent history, and the next inflection point will likely come from megacap earnings, with Alphabet and Microsoft on deck Wednesday (just hours after the Fed), followed by Amazon on Thursday. In the meantime, Anthropic’s S-1 remains the gift that keeps on giving for the circular-deal crowd.
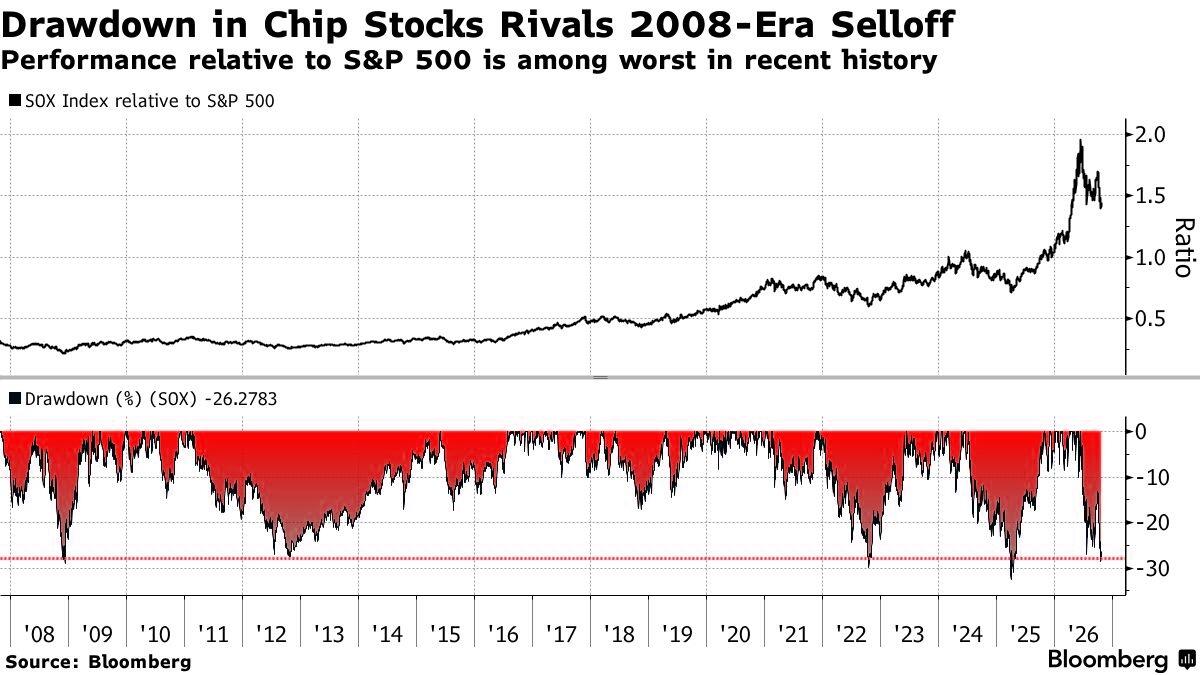
Drawdown in chip stocks rivals the 2008-era selloff: SOX performance relative to the S&P 500 is among the worst in recent history.
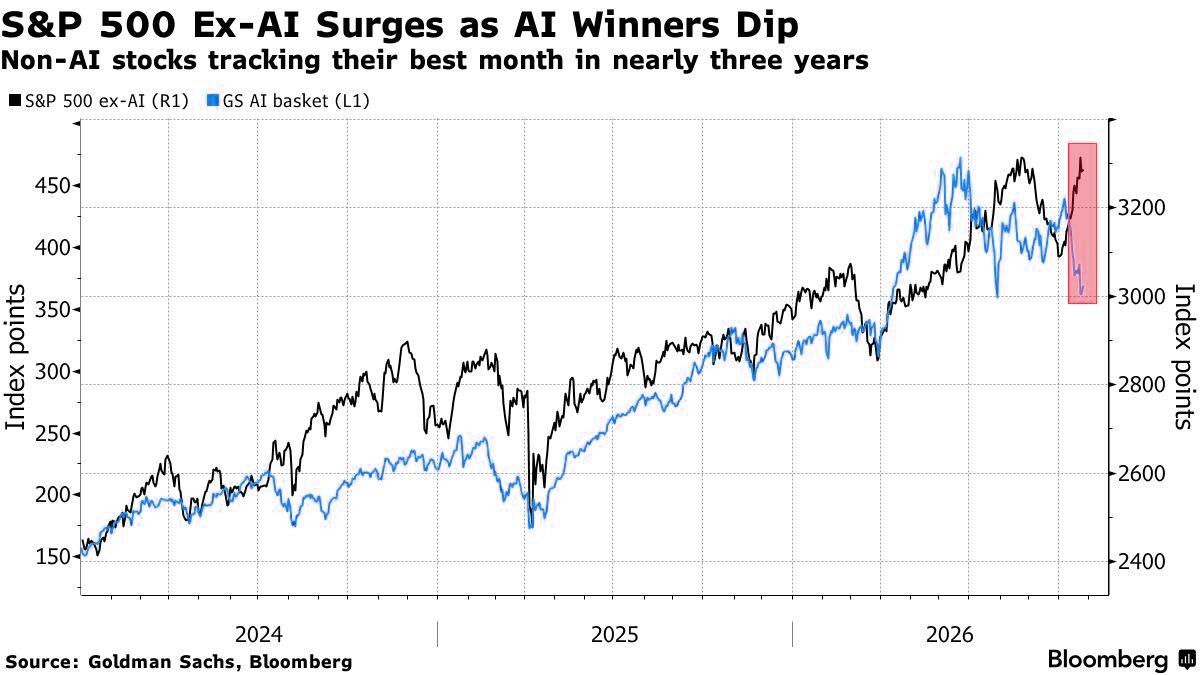
Meanwhile, the gyrations in tech are overshadowing gains in everything else: S&P 500 companies are on track for a 26% jump in quarterly profits, beating the 25% expected, and a basket of S&P 500 stocks excluding AI is up 6% in October, heading for its best month in nearly three years. So far about 26% of the S&P’s market cap has reported, with about 80% beating earnings estimates.
“There’s nothing approaching a full-scale return to risk-on, and nobody has strong incentives to be a hero ahead of a big week and at this time of the year,” said Andrew Tyler, the head of global market intelligence at JPMorgan.
“Most emerging market countries have maintained greater fiscal discipline, so I would not expect Brazil’s turmoil to trigger a broader EM sell-off,” said Rajeev de Mello, global macro portfolio manager at Gama Asset Management. “Fiscal credibility will become an increasingly important differentiator across emerging markets.”
Tyler’s team remains “Tactically Bullish”, arguing that Monday was important in re-establishing the AI theme and that if Oracle’s investor day and the megacap prints (Amazon, Google, Intel, Microsoft) are viewed as bullish, it would create additional momentum into the widely expected post-midterm positive seasonal period and year-end rally. JPM’s Bram notes that ETF investors aggressively bought the semis dip again, with semiconductor ETFs logging a record ~$12.7BN of inflows (SOXX +$6.5BN, SOXL +$2.8BN, SMH +$2.6BN), while CTAs likely sold US and Japan equities as short-term signals turned negative. On the Fed, JPM’s Mike Feroli expects a hold with two hawkish dissents from Hammack and Logan, and quips that Chair Warsh will have to explain why the committee hiked after a two-tenths core PCE print in September but is now holding after an expected three-tenths outturn.
Over at Goldman, Rich Privorotsky observes that “the market struggles to go down, even if people remain reluctant to add risk” but warns that “credit is the one to worry about. Still flashing yellow to red relative to equities.” Goldman’s Ariana Contessa sees “still little signs of offense being played across AI / Tech”, with recent bounces mostly driven by a cessation of high-velocity supply, while Robert Quinn flags that non-dealer net length in Nasdaq futures is at a record after $21.8BN of buying since Sept 29, cautioning that “if announcements from Amazon, Microsoft and Alphabet fail to impress, meaningful futures selling could ensue.” And for those still obsessing over oil, Goldman’s Emma Wade has news: “Tech, not oil, is now driving cross-asset risk.” Citi’s positioning team, meanwhile, says de-risking dominates global futures, with S&P 500 futures adding $11.3 billion of new shorts last week.
Elsewhere, the US may extend a pause on charges for Chinese-linked ships calling at American ports by two months as the two sides iron out broader trade issues, and Trump is set to unveil a plan to dial back federal methane emission requirements for oil and gas operations, part of his push to lower energy costs ahead of the midterms. In Canada, Reuters reports a deal may be forthcoming that eases US tariffs on Canadian autos and steel.
In France, the bond selloff resumed: consumer confidence plunged to 80, the lowest since June 2013 and well below the 85 expected, as households grapple with the bond rout and violent protests, and the OAT-Bund spread widened back above 160bps, erasing roughly half of Monday’s Moody’s-driven tightening.
In Europe, the Stoxx 600 is down 0.1% at 639.87 with 306 members down and 279 up, falling for a third day in four as disappointing earnings from benchmark heavyweight HSBC dragged down banks and pushed the FTSE 100 down about 0.8%. Personal care and autos lag (Mercedes cut its guidance after a slump in China sales, joining VW and BMW), while tech and basic resources outperform. JPM notes semis, power and Ukraine-ceasefire baskets are among the top performers, with China-exposed, diesel and tariff baskets the worst. Here are the biggest European movers:
- BE Semi shares advance as much as 10%, the most since March, after Applied Materials boosted its stake in the Dutch chip-equipment maker to about 20%.
- Ferrovial shares jump as much as 11%, the most in almost six years, after the company said the US I-24 project concession awarded to the consortium it leads is valued at $21 billion.
- SIG Group shares rise as much as 14%, marking a record gain, after the packaging company beat expectations in the third quarter while also raising its margin goal for the year and over the medium-term.
- UMG shares gain as much as 6.2% after Bloomberg reported that the world’s largest record company has discussed going private with a few prominent Wall Street firms.
- Porsche AG shares rise as much as 4.2%, after profitability held up despite another sharp decline in vehicle sales. JPMorgan says the earnings underscore improving momentum for the carmaker in a difficult market environment.
- Novartis shares advance as much as 2.5% after the drugmaker’s third-quarter earnings beat estimates. Analysts note raised outlook for profits and a beat for Cosentyx, the firm’s treatment for chronic inflammatory and autoimmune conditions.
- HSBC shares decline as much as 7.1% in London, making the stock the worst performer Tuesday on the Stoxx 600 Banks Index, after the lender’s 3Q revenue fell short of expectations.
- Wartsila shares drop as much as 8.8%, the most in a year, as Citi says the Finnish engineering company’s medium-term margin targets appear “somewhat light” compared to analyst expectations.
- Reckitt Benckiser shares fall as much as 7.9% after cutting its Core Reckitt like-for-like sales forecast for the full year. The home products retailer also missed on sales, which analysts said was driven by an issue with Lysol manufacturing.
- Beiersdorf shares decline as much as 4.5%, the most since early August, after weakness at adhesives unit Tesa overshadowed a better-than-expected performance in the consumer business that includes Nivea.
- Mercedes-Benz shares drop as much as 5.5%, the most in over a year, after the luxury carmaker cut its profit guidance after sales in China declined. The group joins peers Volkswagen and BMW in downgrading outlook.
- EMS-Chemie shares fall as much as 4.5% after the stock was downgraded to underperform from neutral at Oddo, with analysts saying it’s trading at a level unsupported by earnings revision potential.
Asian stocks advanced, led by South Korean chipmakers, as Anthropic’s IPO filing revived enthusiasm for the AI trade. The MSCI Asia Pacific Index rose as much as 1.1%, with Samsung Electronics and SK Hynix among the biggest gainers. The Kospi jumped 3.1% (up as much as 4.9%, triggering a sidecar) after Q3 GDP beat at +1.0% q/q vs 0.7% expected, the Nikkei gained 1.7% to 63,268 with SoftBank among the leaders thanks to its Anthropic stake, and the ASX rose 0.5%. Hong Kong and mainland China lagged, with the Hang Seng down 0.7% (HSBC slid in Hong Kong after its profit miss) and the CSI 300 down 1.3%, despite China’s industrial profits accelerating to +14.4% in September and a PBOC liquidity injection of more than CNY 1.4 trillion. Goldman’s Privorotsky notes Hynix +5% and Samsung +4%, while in Japan the BoJ’s gauge of underlying inflation jumped to 3.2%, the highest in three years, ahead of Friday’s BoJ decision.
In FX, the Bloomberg Dollar Spot Index is up for a third day but halved its 0.2% advance as oil dropped; the DXY sits at the upper end of a 101.99-102.29 range. EUR/USD fell to a two-week low around 1.1143, about 30 pips from its year-to-date low, as French jitters returned. USD/JPY is little changed near 157.75 after Japan’s FinMin Katayama said the government will respond to FX moves “with a sense of urgency”, while GBP/USD is a touch softer near 1.3325 ahead of Wednesday’s UK Budget. The kiwi leads G10 after the NZIER shadow board recommended an RBNZ rate hike this week.
In rates, Treasuries log small gains, trailing steeper ones for core European bonds, as oil prices dip following the report that Iran’s Supreme Leader discussed aims of ending the war. Front-end and belly yields are 2-3bps richer with the long end lagging slightly, steepening 2s10s and 5s30s by more than 1bp; the 10Y is around 4.97%, near the session low, with bunds and gilts in the sector outperforming by 1.5bps (gilts got an extra lift from reports that Chancellor Healey will raise the minimum wage by nearly 4%, mechanically boosting his Budget headroom). French OATs gave back about half of Monday’s post-Moody’s rally. The auction cycle continues with $70BN of 5Y notes at 1pm ET following Monday’s 2Y sale; the WI 5Y yield around 4.805% is about 23bps richer than last month’s auction, which tailed by 3.1bps (and after yesterday’s tailing 2Y, the bar is not exactly high). The IG dollar slate includes three names so far after Procter & Gamble headlined $17.05BN of issuance Monday. Traders price just a 12% chance of a Fed hike Wednesday and a 90% chance of a 25bp hike in December.
In commodities, crude dipped in Asia, spiked as Europe walked in on reports that missiles targeted Saudi Arabia’s 550k bpd Ras Tanura refinery (Saudi Arabia later said it contained the fire), then reversed lower on the Khamenei headlines; WTI Dec traded in a $100.60-102.82 range and Brent Jan in a $109.53-111.91 range. Sources say OPEC+ is expected to keep December production targets unchanged at Sunday’s meeting, while Energy Transfer declared force majeure at its Nederland LPG terminal. Dutch TTF is down about 1.6%. Spot gold slipped back below $4,000/oz and silver is down about 1.4%, while copper is up about 0.9%.
US economic data slate includes ADP weekly employment (8:15am), September durable goods (8:30am), August FHFA house prices and Case-Shiller (9am), October Conference Board consumer confidence, Richmond Fed manufacturing and September new home sales (10am) and Dallas Fed services activity (10:30am). The Fed is in blackout ahead of Wednesday’s FOMC decision. On the corporate calendar, Visa, Robinhood, Seagate, Teradyne and Waste Management report after the close, and Oracle’s AI World tour runs through Wednesday.
Market Snapshot
Top Overnight News
- Mojtaba Khamenei called for pursuing the conditions set out by Iranian officials with the aim of ending the war during a meeting with Iran’s Supreme National Security Council Secretary Mohsen Rezaee; the meeting also covered Iran’s management of the Strait of Hormuz. BBG
- Iran’s ambassador to South Korea said Iran has proposed a seven-day plan to the US, under which the Strait of Hormuz would reopen on the sixth day if Washington accepts the conditions, with negotiations beginning on the seventh. Newsquawk
- China will send special envoys to the Middle East, adding to efforts to defuse tensions and prevent the resumption of US-Israeli strikes against Iran. BBG
- Saudi Arabia contained a fire near its Ras Tanura oil hub after an attack; the Houthis claimed they targeted the refinery. BBG
- Iran said it will take legal action against Sinokor vessels in the Strait of Hormuz. BBG
- Israelis are voting in their first election since the 2023 Hamas attack, with Benjamin Netanyahu seeking another term in a razor-thin race against an opposition led by former military chief Gadi Eisenkot. BBG
- China’s industrial profits grew at their strongest pace last month since June, as a boom in manufacturing tied to artificial intelligence offset drag from persistently weak domestic demand. CNBC
- South Korea’s economy grew faster than expected in the third quarter as an artificial intelligence-fueled chip boom powered exports and investment, but a contraction in consumption underscored an increasingly uneven expansion that may complicate the trajectory for further interest-rate hikes. BBG
- The BoJ’s gauge of underlying inflation surged to the highest in three years, well above the bank’s 2% target. Consumer prices excluding fresh food and special factors rose 3.2% in September from a year earlier, with the pace quickening from 2.6% in the previous month. BBG
- French consumer confidence plunged to a 13-year low in October as households grappled with a bond selloff and violent protests. Respondents became more worried about finances, living standards and unemployment. BBG
- Flávio Bolsonaro dropped his challenge to Brazil’s election result as his party conceded defeat. Attention now turns to how Lula da Silva will govern as fiscal strains mount and investors question whether he’ll rein in spending. BBG
- Private-equity firms are scrambling to avoid big losses from a potential wave of defaults by the companies they own. Fund managers are racing to negotiate loan extensions on much of a $300 billion wall of debt that is coming due starting in 2028. It is a pressing need that is intensifying because rising interest rates have made refinancing more expensive this year. WSJ
- The United States and Canada are working on a deal to ease US tariffs on Canadian steel and autos, two US and four Canadian sources said, as the two governments try to repair relations that soured after trade talks broke down in August. RTRS
- Meta’s common stock offering was upsized to $25 billion from $22.5 billion, while Broadcom arranged a $63 billion deal to finance the purchase of chips for Anthropic. BBG
- The US plans a two-month extension to its shipping-fee truce with China, pausing charges on Chinese-linked ships calling at American ports. BBG
- Trump is set to unveil a plan to dial back federal requirements designed to slash methane emissions from oil and gas operations. BBG
- The ECB’s bank lending survey showed banks tightened credit conditions and saw loan demand fall, while ECB MRO funding rose to €27 billion, the highest since 2017. BBG
- US President Trump posted “The Trump Administration is proud to announce a 250 MILLION DOLLAR PLUS initiative to RECRUIT and RETAIN Nurses for Nursing Homes!”
- US appeals court denied the Trump administration’s request to stop California from counting mail ballots from alleged non-citizens.
- Goldman’s Jan Hatzius says the firm’s strongest global view is that central banks will deliver fewer hikes than currently priced, with energy the most immediate downside growth risk. GIR
- JPM’s Feroli expects the Fed to hold this week with hawkish dissents from Hammack and Logan, and sees a risk that Kashkari also dissents. JPM
A more detailed look at global markets courtesy of Newsquawk
APAC stocks were ultimately mixed, but with strength seen in tech stocks following the outperformance in the sector stateside as it recovered from the recent AI-led sell-off and with Anthropic filing for an IPO. ASX 200 clawed back initial losses with the index led higher by the commodity-related sectors, but with gains capped as defensives and consumer stocks lagged. Nikkei 225 was underpinned by the tech-related momentum, with SoftBank among the biggest gainers owing to its stake in Anthropic and as it explores AI and digital infrastructure opportunities in Malaysia. KOSPI outperformed and triggered a sidecar amid the tech strength and stronger-than-expected GDP. Hang Seng and Shanghai Comp lagged despite the PBoC’s liquidity boost, with today’s open market operations totalling more than CNY 1.4tln, while continued double-digit percentage growth in YTD Industrial Profits also failed to inspire, as participants await earnings releases and with HSBC shares pressured after its results missed expectations. In addition, trade frictions lingered as the EU plans to impose import restrictions on Chinese chemicals and furniture.
Top Asian News
- Japanese government expert panel discussed revision to three security-related documents, Kyodo reported citing sources, adding that “tax increases should not be ruled out as an option if necessary.”
European bourses are broadly lower, with the FTSE 100 (-0.9%) the laggard following disappointing HSBC earnings (see more below). In terms of a broader driver, newsflow has been light. Overnight, tech stocks continued to rebound from the recent AI-led sell-off, with Anthropic filing for an IPO. Sectors lack a clear bias. Basic Resources top the sector pile, with Tech and Construction closely behind. Optimised Personal Care is the sector underperformer, followed by Autos as Mercedes cut its FY26 guidance, which is weighing on its peers. Key movers include: HSBC -6.9%, PBT and revenue miss estimates; Novartis +1.1%, adj. operating income and EPS beat while lifting its FY26 operating income guidance; BE Semi +8.8%, as Applied Materials plans to raise its stake to 20% (currently 9%); Ferrovial +8.7%, reportedly looking to find a JV partner to finance its data centre campus. US equity futures are mixed, with the NQ underperforming despite a tech rebound overnight. Nvidia and Meta are flat pre-market, as the former plans a USD 3bln investment in Meta’s equity offering. Elsewhere, Cadence Design Systems (+3.1%) is higher pre-market after a Q3 beat and guidance upgrade.
Top European News
- UK Chancellor Healey unveiled five everyday fixes to ease household costs, support working families and end the Carer’s Allowance cliff edge ahead of Wednesday’s Budget, according to the government.
- The European Commission is reportedly exploring using revenues from a global corporate tax agreement targeting large multinationals to fund the EU’s next seven-year budget, Politico reported citing sources.
- French Finance Minister Lescure said France must appease protesters without extra spending and that the government can come up with creative solutions without widening the budget deficit, according to the FT.
FX
- DXY extended Monday’s gains and sits at the upper end of a 101.99 to 102.29 range, comfortably above its 100-DMA (100.60) and 200-DMA (99.59). Currency-specific newsflow has been light, as participants await this week’s slew of risk events, including the FOMC, BoJ and ECB meetings, the UK Budget, US PCE and three Mag-7 earnings reports; ING wrote that higher energy prices and a hawkish Fed can keep the Dollar supported this week, barring clearly underwhelming results from the likes of Alphabet and Microsoft. Today’s US docket includes Durable Goods, Richmond Fed and Dallas Fed Services, while the Israeli election is also in focus, with exit polls due at 20:00GMT/16:00EDT.
- EUR/USD has extended beneath Monday’s 1.1173 trough, and currently holds at the bottom end of a 1.1135 to 1.1177 range, largely moving in tandem with the USD; the pair sits well below its 100-DMA (1.1559) and 200-DMA (1.1632). Options today reside at 1.1175 (EUR 834mln) and 1.1200 (EUR 721mln).
- USD/JPY is incrementally firmer, and holds at the upper end of a 157.42 to 157.89 range, just beneath the 200-DMA at 158.52. Some focus could fall on today’s NY cut (in the absence of macro impulses), which sees a cluster of expiries, most notably at 157.85 (USD 2.1bln), alongside 157.75 (USD 1bln) and 158.00 (USD 1.5bln). On the verbal intervention front, Japan’s FinMin Katayama said the government will respond to FX trade damage with a sense of urgency, while former BoJ Governor Kuroda said the BoJ will likely consider raising rates at each upcoming meeting; overnight, BoJ Core CPI rose to 3.2% (prev. 2.6%), ahead of Friday’s BoJ decision.
- GBP/USD is a touch softer and trades in a 1.3307 to 1.3349 range, holding just beneath its 100-DMA (1.3386) and 200-DMA (1.3429) ahead of tomorrow’s Autumn Budget. The BRC Shop Price Inflation report ticked higher (2.1% vs exp. 1.6%), while The Times reported that Chancellor Healey will announce plans to raise the minimum wage by nearly 4%, but slow the rise for young people. Options see GBP 800mln rolling off 1.3300.
- The Antipodeans outperform, with the NZD higher as the NZIER Shadow Board also recommends a hike, with the RBNZ also expected to hike rates overnight. Australian CPI is also due on Wednesday.
Central Banks
- New Zealand NZIER Shadow Board recommended the RBNZ raise the cash rate this week.
Fixed Income
- An initial modestly firmer bias gave way to relatively flat performance, but with a negative skew from the renewed, but brief, upside in Brent and WTI. More recently, that upside has waned, with fixed benchmarks now picking up a touch, taking USTs into the green by a few ticks.
- The US day is mainly counting down to the FOMC on Wednesday. That aside, the Israeli election is of potential note (exit poll due at 20:00GMT), in case it results in an approach-change to the Middle East conflict.
- Bunds in-fitting with USTs, but with some very modest outperformance, as while the upside in the global energy benchmarks has weighed, Dutch TTF has pulled back slightly from the marked upside on Monday, providing some relative relief. At the time of writing, Bunds hold above the 122.00 handle in 121.96 to 122.23 parameters.
- OATs take a bit of a breather from the rally on Monday, currently lower by about 30 ticks vs upside of around 80 ticks overall that session. As such, the OAT-Bund 10yr yield spread is around 7bps wider, erasing roughly half of the tightening on Monday post-Moody’s.
- Finally, Gilts opened with gains of 13 ticks, before climbing another 31 to an 85.43 peak. Upside driven by the minimum wage reporting being digested, a lift that mechanically provides Chancellor Healey with a significant headroom win. Since, as energy picked up across the morning, this strength has waned somewhat.
- UK sells GBP 4.5bln 4.625% 2032 Gilt: b/c 3.51x (prev. 3.07x), average yield 5.026% (prev. 4.84%), tail 0.3bps (prev. 0.4bps).
- Italy sells EUR 2.0bln (exp. 1.5-2.0bln) 3.00% 2028 BTP: b/c 1.72x (prev. 1.64x), average yield 3.55% (prev. 3.64%).
- Australia sells AUD 1.0bln in 4.75% October 2037 Bonds: b/c 3.12x, avg. yield 5.2051%.
Commodities
- Crude benchmarks dipped in the APAC session amid a lack of major geopolitical escalation, but climbed as Europe stepped in, before paring some of that upside to currently sit in the upper half of today’s ranges but modestly lower on a percentage change. WTI Dec’26 trades within a USD 100.60-102.82/bbl range, and Brent Jan’27 within a USD 109.53-111.91/bbl range; both remain within Monday’s parameters (WTI: USD 100.33-103.13/bbl; Brent: USD 109.22-112.20/bbl).
- The move higher came after Iranian state media IRIB, citing Arab media, reported that Saudi Arabia’s Ras Tanura refinery (550k BPD) was targeted by missiles; reports later suggested the fire was contained. More recently, Saudi Civil Defence issued an emergency alert in Najran, while the Houthis claimed an attack on Abha and Khamis Mushait, with explosions reportedly heard in both cities and at Khamis Mushait Air Base; Saudi Civil Defence has since said the danger has passed. Elsewhere, sources said OPEC+ is expected to maintain December oil production targets at Sunday’s meeting.
- Dutch TTF is lower by c. 1.6%, within a EUR 94.85-96.70/MWh range. Iranian President Pezeshkian met Qatar’s Emir at the GECF summit in Moscow, where they discussed expanding energy cooperation, while Press TV reported that Iran, Russia and Azerbaijan are discussing a gas swap agreement.
- Spot gold slipped back beneath the USD 4k/oz mark in the European morning, and sits towards the bottom end of a USD 3,989-4,026/oz range alongside the firmer Dollar, well beneath its 100-DMA (USD 4,218/oz) and 200-DMA (USD 4,504/oz). Spot silver is lower by c. 1.4% within a USD 52.67-54.23/oz range.
- Copper is firmer, with CME copper futures up c. 0.9% and at the top of a USD 6.54-6.60/lb range, having edged higher overnight alongside the tech-related momentum in stocks. 3M LME copper trades in a USD 14,322.18-14,446.72/t range.
- US President Trump is to ease oil well methane curbs in a bid to lower costs.
- OPEC+ is reportedly expected to maintain December oil production targets at Sunday’s meeting, according to sources.
- Singapore and France are to deepen cooperation on electricity and gas, while Singapore and New Zealand will also strengthen energy cooperation.
Trade/Tariffs
- USTR Greer issued a statement regarding the status of the US-EU deal to pause duties on certain EU imports, while he stated that European Investment Bank loans to Airbus (AIR FP) may be a violation of the US-EU trade truce and it is important that the situation is resolved as soon as possible.
- German Chancellor Merz said the EU seeks closer partnership with ASEAN and is complementary to talks between the EU and Canada. Regarding CPTPP collaboration, Merz said that the EU, with 450mln consumers, has strategic interest in having open access to markets.
Geopolitics: Middle East
- The Iranian Ambassador to South Korea said Iran has proposed a seven-day plan to the US and is preparing a response to US feedback, adding that Iran does not want war and seeks to reduce tensions through diplomacy. Additionally, the ambassador said that the Strait of Hormuz would reopen on the sixth day if Washington accepts the conditions, with negotiations beginning on the seventh day.
- Iran’s Supreme National Security Council Secretary General Rezaei said security in West Asia must be devoid of foreign interference, following the conclusion of quadrilateral talks involving Iran, Pakistan, Turkey and Saudi Arabia in Tehran, according to Press TV.
- IRGC Supreme Leader’s representative warned that Iran knows the enemy’s vulnerabilities and would deliver a more devastating response than before if attacked again.
- A Houthi official said Egypt’s parliament authorising military support for Saudi Arabia amounts to a declaration of war against Yemen, AFP reported.
- Saudi-led coalition intercepted three Houthi ballistic missiles aimed at the eastern region, while it also intercepted four drones launched by Yemen’s Houthis towards the southern region.
- Saudi Arabia’s Ras Tanura refinery (550k BPD) was reportedly targeted by missiles, triggering powerful explosions and large plumes of smoke, IRIB reported. Following this, Saudi Arabia said it contained the fire near the Ras Tanura oil hub following an attack.
- Explosions were reportedly heard at Prince Sultan Air Base in Saudi Arabia, while Saudi Civil Defence said sirens sounded in Al-Kharj and the Eastern Province, ISNA reported.
- Saudi airstrikes reported on port of Mokha and surrounding areas in Yemen, according to SNN.
Geopolitics: Ukraine
- Russian Defence Ministry said Russia suspended strikes on Ukraine’s Kherson as a ceasefire began in Oleshky.
- Russian Defence Ministry said Russian forces struck a cargo ship in the Black Sea and an industrial facility producing drones in Kyiv, according to IFX.
- Russian attacks targeted Kyiv’s transport infrastructure and logistics hub in the Kharkiv region.
- Explosions were heard in Ukraine’s capital, Kyiv, according to reports citing a witness.
Geopolitics: Other
- Taiwan considers drone swarms as a defence measure against Beijing’s grey-zone operations, according to the South China Morning Post.
Crypto
- Bitcoin remains contained within Monday’s parameters, as the cryptocoin falls below USD 80k.
US Event Calendar
- 8:15am: ADP Weekly Employment Change
- 8:30am: Sep P Durable Goods Orders, est. 1.9%, prior -0.1%
- 8:30am: Sep P Durables Ex Transportation, est. 0.6%, prior 0.2%
- 8:30am: Sep P Cap Goods Orders Nondef Ex Air, est. 0.7%, prior 1.6%
- 9:00am: Aug FHFA House Price Index MoM, est. 0.2%, prior 0.3%
- 9:00am: Aug S&P CoreLogic Case-Shiller home prices
- 10:00am: Oct Conf. Board Consumer Confidence, est. 81.0, prior 81.9
- 10:00am: Oct Richmond Fed Manufact. Index, est. 0, prior -2
- 10:00am: Sep New Home Sales, est. 651k, prior 684k
- 10:30am: Oct Dallas Fed Services Activity
- 11:30am: $54bn 52-week bill and $95bn 6-week bill auctions
- 1:00pm: $70bn 5-year note auction
Central Bank Speakers
- None: the Fed is in its external communications blackout ahead of Wednesday’s FOMC decision
DB’s Jim Reid concludes the overnight wrap
After a night of freedom while my family headed off to Centre Parcs yesterday, my brief spell of peace and reflection is nearly over. After work today, I’m driving to join them for a couple of days. So while you’re all focused on major tech earnings and the FOMC, against my will I’ll be zip-wiring, aerial roping, kayaking, swimming, trying not to sink in the rapids, and, of course, paying the bills. Spare a thought for me.
Markets have started the week in a broadly optimistic mood, with the S&P 500 (+0.70%), Nasdaq Composite (+0.82%) and STOXX 600 (+0.77%) all advancing yesterday, whilst longer-dated bonds mostly rallied. The OAT-Bund spread tightened -13.8bps to 153bps, which is the biggest daily narrowing since March 2020. But politics remained firmly on the radar, with Brazilian assets selling off sharply after President Lula’s surprise election victory over Flávio Bolsonaro, leaving the Bovespa down -13.88% and the real -8.06%, the worst USD adjusted day for domestic equities in nearly 35 years but not as bad as this time yesterday. And today brings another potentially much more consequential election for global markets in Israel, not least because of what the result could mean for the next phase of the confrontation with Iran. Oil markets remain volatile, with both Brent (-0.78% to $115.81/bbl) and WTI (-1.46% to $101.76/bbl) eventually settling slightly lower amid news of talks between Iran and the Mecca Pact countries.
Starting with equities, the positive tone saw the Philadelphia Semiconductor Index rise +2.82% after falling -3.21% last week, whilst the Mag 7 gained +0.76%. Some of the recent AI-related underperformers also rebounded, including CoreWeave (+1.76%), despite initially falling in pre-market trading after Elon Musk wrote on X on Sunday that “neoclouds” would see “guppy-level death and consolidation”, arguing that debt markets would be reluctant to finance companies overwhelmingly reliant on AI data centres for their revenues. Meta (-1.88%) dipped after announcing plans to raise as much as $95bn through a stock sale. Meanwhile, Microsoft (+1.54%) gained after announcing that it will offer buyouts to about 60,000 employees as part of an effort to trim costs. Europe joined the rally too, with the DAX (+0.91%), CAC 40 (+0.83%) and FTSE 100 (+0.72%) all advancing.
There was also some more encouraging news from the Middle East yesterday, although the overall daily move was muted as investors remain wary of extrapolating too much from the latest diplomatic efforts. Senior officials from Saudi Arabia, Turkey and Pakistan – which form the Mecca Defence Alliance – met Iranian representatives in Tehran in the hope of promoting greater regional stability, with state-run IRIB reporting that Iran would support “any understanding” that strengthened regional unity. That comes after reports last week that the US and Israeli militaries had begun drawing up plans for renewed strikes on Iran.
The positive read across from those diplomatic developments was partially offset by Reuters reporting that Hezbollah was preparing for a possible resumption of hostilities with Israel, with Brent reaching $117.44/bbl intra-day after the report. But the more upbeat news dominated in the end, with Brent settling -0.78% lower at $115.81 and trading another -1.04% lower this morning. By contrast, European natural gas futures climbed +3.01% to a new post-2022 high of €96.68/MWh amid a supply outage in Norway, even as US natural gas prices (-1.44%) fell to a 6-month low amid the warm weather.
In Europe, France was the biggest story. 10yr OAT yields fell -11.6bps after Moody’s surprised the market on Friday by leaving France’s credit rating unchanged. The weekend protests were also controlled in a way the previous weekend’s weren’t. That all helped the OAT-Bund spread tighten -13.8bps to 153bps, its largest one-day decline since March 2020, with the move amplified by 10yr Bund yields rising +2.2bps. Elsewhere, 10yr BTP yields fell -8.2bps and gilt yields were down -1.2bps. At the front end, 2yr Bunds rose +4.9bps with French (-4.5bps) and Italian (-2.5bps) lower. There was likely some unwinding of flight to quality here too, while bund yields were also boosted by the energy component as well as a stronger-than-expected IFO survey reading that saw the expectations component rise to its highest since 2022 at 91.6 (vs. 90.0 expected).
In the US, 2yr Treasury yields (+3.5bps) reversed some of last week’s decline amid the risk-on tone, although longer maturities rallied amid the pullback in US energy prices, leaving 10yr Treasury yields -0.7bps at 4.99%.
Asian equity markets are mostly trading higher this morning but US and European futures are slightly lower. Within the region, the KOSPI (+3.27%) is outperforming, led by strong advances in heavyweight chipmakers Samsung Electronics (+4.23%) and SK Hynix (+6.12%). Sentiment has also been boosted by stronger-than-expected third-quarter GDP data from South Korea (details below). Elsewhere, the Nikkei (+1.55%) is posting solid gains, while Australia’s S&P/ASX 200 (+0.49%) is also higher. In contrast, Chinese equities are underperforming the broader regional rally, with the CSI 300 (-0.39%), Hang Seng (-0.64%), and Shanghai Composite (-0.45%) all trading lower. S&P 500 (-0.09%), Nasdaq (-0.38%) and Stoxx (-0.41%) are all lower with 10-year US Treasury yields -2.1bps lower at 4.968% as we go to print.
Earlier, Chinese industrial profits accelerated in September, driven primarily by strength in AI-related industries, while consumer-facing sectors continued to face headwinds from weak domestic demand. Industrial profits rose 14.4% y/y in September, marking the fastest pace of growth since June. For the first nine months of 2026, profits at large industrial firms increased 15.5%, marginally below the 15.7% growth recorded over January-August.
Turning to South Korea, the economy expanded faster than expected in the third quarter of 2026 as robust global demand for advanced AI chips continued to support growth. GDP rose +3.4% y/y in the three months to September, exceeding expectations of +3.0%, although moderating from 3.7% growth in the previous quarter. On a quarterly basis, GDP increased +1.0%, ahead of consensus forecasts for a +0.8% rise.
Another election worth watching today is in Israel, and potentially a much more important one for global markets. Neither Benjamin Netanyahu’s bloc nor the opposition led by former military chief Gadi Eisenkot currently appears to have a clear route to the 61 Knesset seats needed for a majority, with the smaller parties, the 3.25% electoral threshold, and potentially the Arab parties likely to prove crucial to the eventual coalition arithmetic. Our economists think that leaves everything from another Netanyahu-led government to an opposition or unity government, political deadlock and potentially another election on the table.
But the bigger global question is what the result means for Iran. There is broad agreement across the Israeli political mainstream on preventing Iran from acquiring a nuclear weapon, so an opposition victory shouldn’t necessarily be interpreted as a dovish outcome. However, there is an important difference over the endgame. Eisenkot has said Israel should be prepared to intervene militarily if necessary to prevent an Iranian nuclear weapon, whilst stopping short of pursuing regime change. Netanyahu, by contrast, has maintained that regime change is ultimately necessary to remove the Iranian threat. That distinction could matter considerably if tensions re-escalate after the US midterms. So today’s vote won’t remove the prospect of another confrontation with Iran, but it could have an important bearing on what Israel ultimately wants any confrontation to achieve. So the aftermath and coalition arithmetic will be very relevant well beyond Israel.
To the day ahead now, US data includes the October Conference Board consumer confidence index, Richmond Fed manufacturing and business conditions indices, September durable goods orders and new home sales. In Europe, we’ll get France’s October consumer confidence and Eurozone September M3. It will also be a busy day for earnings, including Visa, HSBC, NXP Semiconductors, Teradyne and Boeing. Finally, the US Treasury will auction $70bn of 5yr notes.
Source: https://freedombunker.com/2026/10/27/futures-rise-oil-slides-as-irans-supreme-leader-talks-peace-and-shrugs-off-ras-tanura-attack/
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,836,252,329 |
| Stories: | 8,727,448 |
Whistler Blowers, Insiders

