Turning Savings Into a Paycheck: How Retirement Income Actually Works
Nearly all retirement advice addresses accumulation. Save consistently, invest broadly, leave it alone, let time do the work. The guidance is sound and the mechanics are not complicated.
Then you stop working, and the problem inverts. Instead of adding to a balance on a schedule, you are drawing from several accounts with different tax treatments, coordinating that with Social Security, managing Medicare premiums that respond to your income, and doing all of it against an unknown lifespan and an unknown sequence of market returns.
The second problem is considerably harder than the first, and the decisions are largely irreversible.
The three buckets
Most people arrive at retirement with money in some combination of three categories, and the differences drive nearly everything else.
Tax deferred. Traditional 401(k) and IRA balances. Nothing was taxed going in and everything is taxed as ordinary income coming out. Subject to required minimum distributions later.
Tax free. Roth accounts. Contributions were taxed already, qualified withdrawals are not taxed, and Roth IRAs have no required distributions during the owner’s lifetime.
Taxable. Ordinary brokerage accounts. You owe tax on dividends and realized gains, with long term capital gains taxed at preferential rates, and holdings generally receive a step up in basis at death.
The order in which you draw from these changes your lifetime tax bill meaningfully, and the conventional sequencing advice is frequently not optimal.
Why sequencing matters
The standard rule of thumb says spend taxable first, then tax deferred, then Roth. It is a reasonable default and it often leaves money on the table.
The reason is that draining taxable accounts first can leave several years in very low tax brackets, followed by a sharp increase once required distributions and Social Security both begin. Lifetime taxes are usually lower when income is spread more evenly across years rather than left low and then spiking.
This is why blended withdrawals, taking from more than one bucket in the same year to fill a target bracket deliberately, frequently beat a strict order. Getting this right is one of the clearer places a financial advisor adds measurable value, because the calculation depends on your specific balances, brackets, and timeline.
The gap years
The period between retiring and the start of required distributions and Social Security is the most valuable planning window most people will ever have, and it is routinely wasted.
During those years, income can be unusually low, which creates room for Roth conversions at favorable rates. Converting tax deferred money to Roth means paying tax now to reduce future required distributions and future taxable income.
The window closes. Once Social Security and required distributions begin, the space disappears. People who recognize this at seventy five are looking back at a decade of missed opportunity.
Conversions are not universally advantageous. They depend on current versus expected future brackets, available cash to pay the tax, estate plans, and how the conversion interacts with other thresholds. Franklin Wealth, a financial advisor in Chattanooga, runs this analysis against a client’s actual balances rather than a rule of thumb.
Social Security timing
You can claim between sixty two and seventy. Full retirement age is sixty seven for anyone born in 1960 or later.
Claiming early permanently reduces the benefit. Delaying past full retirement age increases it by roughly eight percent per year until seventy. Those adjustments are permanent and they are indexed for inflation, which compounds the effect over a long retirement.
The married calculation is more complex than the single one, and the key consideration is often the survivor benefit. When one spouse dies, the survivor keeps the larger of the two benefits. That makes the higher earner’s claiming decision partly a decision about the survivor’s income for the rest of their life, which is an argument for the higher earner delaying that has nothing to do with break even math.
Health, longevity expectations, cash flow needs, and tax interactions all factor in. Claiming at sixty two is right for some people and expensive for others.
Required minimum distributions
Tax deferred accounts eventually require withdrawals. Under current law the starting age is seventy three, rising to seventy five in 2033.
The amount is formula driven and increases as a percentage over time. For people with large tax deferred balances, required distributions can push them into higher brackets and trigger other thresholds regardless of whether they need the money.
This is the problem that Roth conversions during the gap years are largely designed to address.
The thresholds that create cliffs
Several rules create sharp effects at specific income levels rather than gradual ones, and crossing them accidentally is a common and avoidable cost.
Medicare premium surcharges. Premiums increase at defined income thresholds, based on your income from two years earlier. Exceeding a threshold by a small amount produces the full surcharge.
Social Security taxation. How much of your benefit is taxable depends on a formula combining other income with half your benefit, which creates ranges where additional income is taxed at an unusually high effective rate.
Capital gains rates. Long term gains are taxed at zero up to a threshold, which is a genuine opportunity in low income years.
Marketplace health insurance subsidies, for anyone retiring before sixty five. These phase out with income, which interacts directly with Roth conversion decisions during exactly the years conversions are most attractive.
Sequence of returns risk
Two retirees can experience identical average returns over thirty years and end up in very different positions depending on when the poor years occurred.
Losses early in retirement, while withdrawals are being taken, do lasting damage because shares sold at depressed prices cannot participate in the recovery. The same losses later are far less consequential.
The common response is holding one to three years of expenses in cash or short term instruments, so that market declines do not force selling at the worst moment. It is unglamorous and it addresses a real risk.
On withdrawal rules
The familiar four percent guideline came from research on historical outcomes and was never intended as a lifetime rule.
It assumes a fixed portfolio, a thirty year horizon, and inflation adjusted withdrawals regardless of circumstances. Real retirees do not spend that way, and a flexible approach that adjusts in poor years generally supports a higher initial rate than a rigid one.
Treat it as a reference point rather than a plan.
Guaranteed income
Some retirees fill part of the gap between essential expenses and Social Security with an annuity that provides guaranteed lifetime income. The simplest versions are straightforward and address longevity risk directly.
The considerations are real: cost, loss of liquidity, inflation protection, insurer strength, and the fact that complexity in this category varies enormously between products. Simple ones are easier to evaluate than complex ones for good reason.
Pulling it together
These decisions interact. Claiming Social Security affects taxable income, which affects Medicare premiums, which affects how much room exists for Roth conversions, which affects future required distributions.
Optimizing each piece separately usually produces a worse result than coordinating them, which is why retirement income planning tends to warrant professional help more than accumulation does.
Franklin Wealth works with clients on retirement income planning, including the sequencing and conversion decisions that have to be made during the years when the window is open.
The savings rate was the thing you controlled during your career. Coordination is the thing you control now.
This article is general educational information and not personalized investment, tax, or legal advice. Tax rules change and thresholds are adjusted periodically. Consult a qualified professional about your specific circumstances.
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
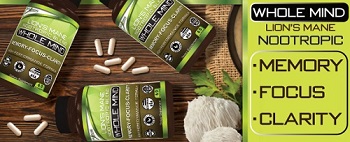
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,834,843,851 |
| Stories: | 8,720,255 |
Whistler Blowers, Insiders

