Central Banks Cannot Fix The Sovereign Debt Bubble
Authored by Daniel Lacalle via dlacalle.com,
Global investors spend a great deal of time worrying about an alleged artificial intelligence bubble. However, they should pay more attention to the government debt bubble. The most dangerous assumption is that governments can keep borrowing and making promises because central banks will always step in, disguising fiscal irresponsibility with quantitative easing programs. Many market participants hail debt accumulation and expanding government size in the economy because they believe it will create asset inflation forever. However, encouraging malinvestment and complacency is a poor long-term strategy.
Furthermore, buying government bonds does not create the wealth needed to pay for those promises. Many pension funds and Keynesian market participants are discovering that supporting constant government expansion is not profitable. The massive losses in some complacent bond portfolios show the mistake. The Bloomberg Global Aggregate Index remains significantly underwater from its early 2021 peak, sitting at an overall net decline of approximately 16% as of September 25, 2026. Smart bond investors have steered away from duration and government debt, concentrating their strategies on credit, low duration, and private debt.
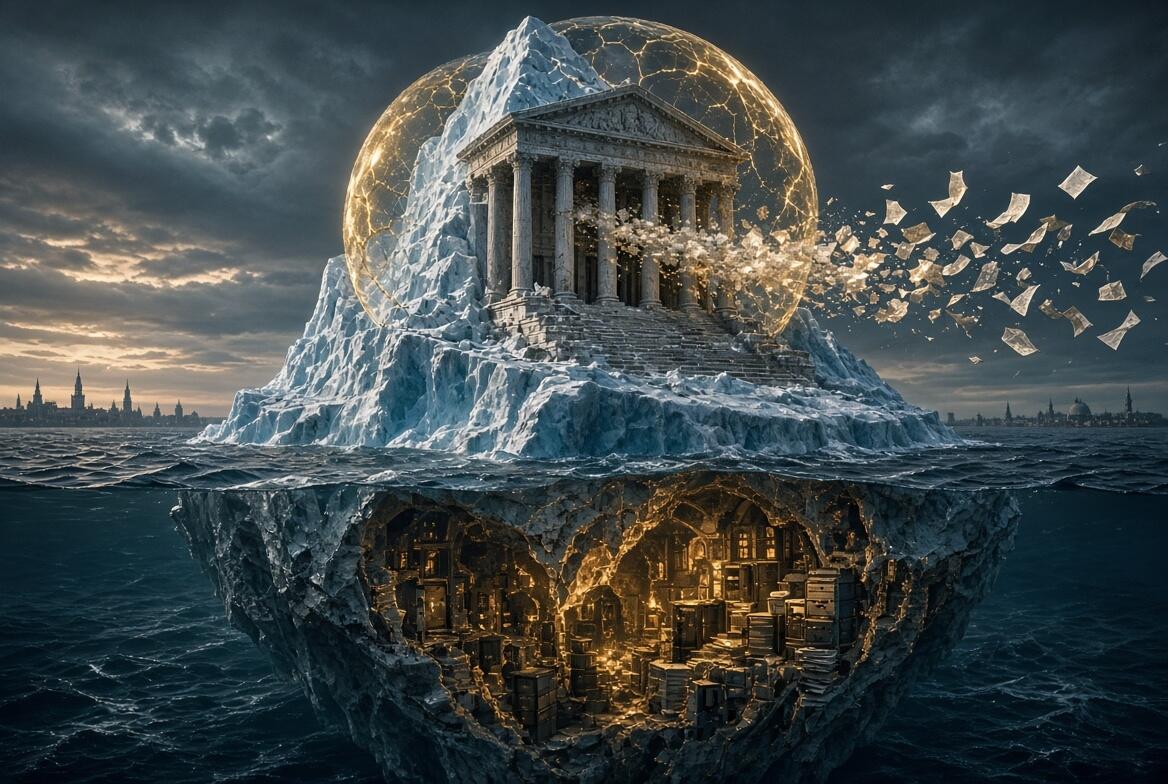
Public debt is like a massive iceberg. The bonds that have already been issued are the visible part of the iceberg. However, the 94% global public debt to GDP only tells a small part of the story. Below the surface are unfinanced commitments to pensions, healthcare, and other spending that have no adequate funding and add up to 300% of GDP. Looking only at outstanding debt provides us an incomplete picture of what taxpayers may eventually have to finance. Even worse, it gives a wrong view of government solvency.
The IMF projects global public debt will reach 100% of GDP by 2029, with the increase driven by major economies. Thus, this problem extends well beyond the emerging markets usually associated with debt crises.
The United States provides a clear example. Treasury’s fiscal 2025 financial report puts federal debt held by the public at 99% of GDP and separately reports approximately $88.4 trillion in projected social insurance funding shortfalls, measured in present-value terms over 75 years.
That figure measures the gap between projected benefit payments and dedicated revenues, discounted into today’s dollars, and depends on assumptions about future conditions. Nonetheless, these are spending promises that require financing or changes to the rules.
The pressure will become harder to manage if governments continue postponing spending cuts and structural reforms. Rising demands for social spending and defense added to increasing interest burdens make the situation worse. Every government may consider all its spending plans essential, but calling them essential does not make them affordable.
The political incentives are evident. Politicians can announce benefits today and leave future taxpayers to cover the cost. As populism takes over, promises become larger and solvency weakens.
Cutting spending attracts opposition immediately, whereas borrowing seems to be hailed and postpones the argument. However, refusing to choose between competing priorities does not remove the cost. The bill is passed to someone else and under worse conditions.
Central banks can make borrowing easier and help governments disguise the problem for a while. Lower interest costs can provide some relief. However, governments use that relief to increase spending instead of repairing their finances. Thus, the underlying problem keeps growing.
Quantitative easing may calm markets and reduce risk premiums for a while. However, central banks do not print solvency, and bond purchases do not make permanent overspending sustainable.
Furthermore, QE does not make the public sector’s obligations disappear. When a central bank buys long-term government bonds using interest-bearing bank reserves, it effectively replaces longer-term borrowing with liabilities whose cost moves with overnight interest rates, according to the Bank For International Settlements. Viewed together, the government and central bank become more exposed to increases in short-term rates, not less. Once we understand this situation, we also see why inflation is rising. Central banks and governments are eroding the purchasing power of the currency by issuing too much money-debt compared to the private sector demand. Additionally, higher taxes constantly weaken the private sector. All this combined leads to stagnation and persistent inflation.
Consider a simple example. A government saves one percentage point of GDP in interest costs but increases its deficit before interest payments by the same percentage point. Additional overspending has more than absorbed the cheaper financing. Thus, a monetary intervention in the bond market coexists with a worsening fiscal position.
Governments have grown accustomed to the idea that they can spend more during growth periods and even more during recessions. As such, the placebo effect of central bank intervention lasts less every time.
There is also a problem with incentives. If politicians expect the central bank to intervene whenever borrowing becomes uncomfortable, they will never make difficult spending decisions. Each bailout can buy time, but time is useful only if governments use it to change course. Governments use easing periods to announce even more spending and pretend that their policies work.
Financial repression is also shifting the burden while impoverishing citizens. Governments can steer savings towards public debt, but they keep returns below inflation, reducing the real value of what they owe.
The sad truth is that no government is going to provide savers a real economic return when investing in their debt. It is a real and many times nominal loss.
Savers and taxpayers pay through lost purchasing power. As governments then use the savings to finance more deficits, citizens suffer without gaining healthier public finances. Taking purchasing power from savers does not make debt affordable; it makes everyone poorer.
Ignoring the problem and delaying spending cuts also makes the adjustment harder. Treasury estimates that delaying fiscal reform until 2036 would increase the average adjustment needed from 4.7% to 5.6% of GDP. Waiting for the next central-bank intervention is therefore a comfortable but costly political choice.
The solution comes from cutting spending and reforming committed programs before a crisis forces abrupt changes. Stronger productivity, private investment, and competition must also be part of the answer. Governments cannot keep weakening the productive economy with ever-increasing taxes while expecting it to finance ever-larger promises.
Central banks cannot fix the sovereign debt bubble. The short-term placebo effect fades away faster every time, regardless of the size of the purchase plan. QE and financial repression did not buy time, because governments did nothing and left the underlying problem unresolved. Citizens are paying for the same irresponsibility through inflation, weaker growth, lower real net wages, and higher taxes. The absence of a bond-market crisis today does not mean the problem has disappeared; it is just eroding the productive economy through crowding out and financial repression.
The next time you hear a politician promising free stuff, remember that you will pay for it many times over.
Tyler Durden Thu, 10/01/2026 – 06:00
Source: https://freedombunker.com/2026/10/01/central-banks-cannot-fix-the-sovereign-debt-bubble/
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,833,543,302 |
| Stories: | 8,713,157 |
Whistler Blowers, Insiders

