How to Plan for Everyday Expenses During a Long Legal Case
A long legal case can affect more than your schedule. If an injury keeps you from working or reduces your hours, regular expenses may become harder to cover while your case is still pending.
Rent, mortgage payments, utilities, groceries, insurance, transportation, and medical costs continue regardless of how quickly a claim moves forward. A case that takes several months or longer can put pressure on even a carefully managed household budget.
Planning early can help you protect your cash reserves, prioritize essential bills, and avoid financial decisions that create additional problems later.
Start With Your Current Monthly Expenses
Before changing your spending, calculate how much money your household actually needs each month.
Review your bank and credit card statements for the previous three months. Divide your expenses into three groups:
-
Essential expenses, such as housing, utilities, groceries, transportation, insurance, and necessary medical care
-
Adjustable expenses, such as dining out, entertainment, subscriptions, and nonessential shopping
-
Debt payments, including credit cards, personal loans, auto loans, and other recurring obligations
Be specific. A rough estimate can make your financial situation look better or worse than it really is.
For example, suppose your household normally spends $4,200 per month. After reviewing your expenses, you determine that $3,100 covers essential bills, $650 goes toward debt payments, and $450 covers discretionary spending. You now have a clearer idea of where reductions are possible.
Calculate How Long Your Savings Could Last
Once you know your minimum monthly expenses, compare that amount with your available cash.
If you have $12,000 in accessible savings and need approximately $3,000 per month for essential expenses, you have about four months of coverage if no additional income comes in.
Avoid assuming that your legal case will resolve before your savings run out. Settlement timelines can change because of medical treatment, negotiations, disputes over liability, insurance issues, discovery, or court scheduling.
Instead, consider several scenarios. Build a budget for the next three months, six months, and 12 months. This gives you a clearer picture of what you would need to change if the case lasts longer than expected.
Prioritize Housing and Basic Services
When money becomes tight, decide which bills have the greatest immediate impact on your household.
Housing should usually be near the top of the list. Rent or mortgage problems can quickly become serious. Electricity, water, basic phone service, groceries, transportation, insurance, and necessary medical expenses also deserve priority.
If you know you may have trouble paying a bill, contact the provider before the payment is late. Some mortgage companies, landlords, utilities, lenders, and medical providers may offer payment arrangements or temporary hardship options.
Ask specific questions about eligibility, fees, interest, reporting practices, and repayment terms. Get important agreements in writing.
Adjust Your Budget Based on Your Current Income
If an injury reduces your income, your previous budget may no longer work.
Suppose your household previously brought home $6,000 per month and spent $5,200. After an accident, income drops to $4,100. Even if spending stays exactly the same, you now face a $1,100 monthly shortfall.
Look for expenses you can reduce without affecting essential needs. You might temporarily cancel unused subscriptions, reduce restaurant spending, postpone large purchases, or renegotiate certain service plans.
Small cuts can add up. Reducing expenses by $50 on subscriptions, $150 on dining, $100 on entertainment, and $200 on nonessential purchases frees up $500 each month. Over six months, that equals $3,000.
Keep Legal Case Money Separate From Your Regular Budget
Do not treat a possible settlement as money you already have.
Even when a case appears strong, the final amount and payment date may remain uncertain. Settlement negotiations can take time, and additional steps may be required before you receive funds.
Build your household budget around money that is currently available or reasonably predictable. This could include wages, a spouse’s or partner’s income, disability benefits for which you qualify, insurance payments, or other established income sources.
Your attorney can provide information about the status of your case, but an estimated timeline should not replace a practical household budget.
Understand Your Options Before Borrowing
If savings and current income cannot cover essential expenses, you may start considering borrowing options.
Compare them carefully.
Credit cards can provide immediate access to funds, but high interest rates can make balances expensive if you cannot repay them quickly. Personal loans may offer fixed payments, although approval and rates usually depend on factors such as credit history and income.
Some plaintiffs also research legal funding for personal injury lawsuits when they need help covering expenses while a qualifying claim remains unresolved. Before agreeing to any type of funding, review the total repayment amount, fees, terms, and what happens if the case resolves differently than expected.
When researching a company, check independent sources as well. For example, you can review a provider’s Better Business Bureau business profile for available company information, complaint history, ratings, and other details.
Do not focus only on how much money you can receive today. Calculate what the option could cost you later.
Plan for Medical Expenses That May Continue
Medical costs can remain unpredictable during a personal injury case.
You may have recurring appointments, physical therapy, prescription costs, diagnostic testing, transportation expenses, or medical equipment needs. Some expenses may occur weekly or monthly rather than as a single bill.
Create a separate category in your budget for ongoing medical costs. If you spent $600 last month on treatment-related expenses, for example, do not automatically assume next month’s cost will be zero.
Ask providers about upcoming treatment and expected out-of-pocket costs when possible. Keeping copies of bills, receipts, insurance statements, and payment records can also help you maintain an accurate financial picture.
If you want general background on how personal injury claims work, personal injury resources for plaintiffs can help you become familiar with common legal topics while you continue discussing the specifics of your case with your attorney.
Create a Weekly Spending Limit
A monthly budget can feel difficult to manage when money is tight. Breaking it into weekly limits can make spending easier to track.
Suppose you have $800 available each month for groceries, fuel, household supplies, and other flexible necessities. Instead of treating the entire $800 as immediately available, set a target of roughly $185 per week and keep a small amount in reserve.
Review your spending at the same time each week. Ten minutes every Sunday, for example, may be enough to identify whether you are staying within your target.
If you overspend one week, adjust the following week rather than waiting until the end of the month.
Build a Small Emergency Buffer
Even during a financially difficult period, try to keep some cash available for unexpected expenses.
A car repair, higher utility bill, prescription, or urgent home expense can disrupt a budget quickly. If possible, avoid using every dollar of savings for predictable monthly bills.
Your emergency reserve does not need to be large. Even $500 or $1,000 can prevent a relatively small surprise expense from immediately going onto a credit card.
The appropriate amount depends on your household, transportation needs, health expenses, and available income.
Review Automatic Payments
Automatic payments are convenient when your income is stable. They can cause overdraft fees when your account balance becomes unpredictable.
Make a list of every automatic withdrawal connected to your checking account and credit cards. Include streaming services, software subscriptions, memberships, insurance premiums, loan payments, phone bills, and other recurring charges.
Cancel services you no longer need. For necessary bills, confirm the withdrawal dates and amounts.
A simple calendar can help. If your rent is due on the first, insurance on the fifth, phone bill on the tenth, and car payment on the fifteenth, you can see how much cash needs to remain available at different points during the month.
Avoid Making Financial Decisions Based on an Expected Settlement
It can be tempting to postpone financial planning because you expect compensation from your case.
That approach carries risk.
The amount you ultimately receive may differ from an early estimate. Attorney fees, case expenses, medical bills, liens, or other obligations may affect the net amount available to you. The timing can also change.
Avoid taking on major new expenses solely because you expect a settlement. Wait until you understand the actual amount available to you before making large purchases or long-term financial commitments.
Keep Your Financial Records Organized
Good records make it easier to understand where your money is going and can help you provide information to your attorney when appropriate.
Keep documents such as:
-
Medical bills and receipts
-
Prescription receipts
-
Pay stubs
-
Records showing missed work
-
Disability or insurance payment records
-
Transportation expenses related to treatment
-
Bank statements
-
Loan or funding agreements
-
Correspondence about payment plans
You can keep digital copies in organized folders by month or expense type. Update them regularly instead of trying to reconstruct several months of financial activity later.
Revisit Your Plan Every Month
Your financial situation can change during a long legal case.
You may return to work, face additional treatment, receive insurance benefits, reduce certain expenses, or experience a longer case timeline than expected. Your budget should change with your circumstances.
At the end of each month, compare what you planned to spend with what you actually spent. If your essential expenses were $300 higher than expected, determine whether that increase was temporary or likely to continue.
Then update your next three to six months of projections.
Focus on the Expenses You Can Control
You may have limited control over how long your legal case takes, but you can make deliberate decisions about your household finances while it continues.
Start with accurate numbers. Identify your minimum monthly expenses, calculate how long your available cash may last, reduce flexible spending, and plan for ongoing medical costs. Review borrowing or funding terms carefully before signing an agreement, and keep some money available for unexpected expenses when possible.
Most importantly, update your plan as your income, expenses, treatment, and case circumstances change. A realistic budget gives you a clearer view of what you can afford today without depending on money you may receive later
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
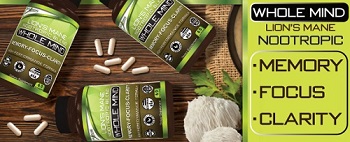
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,833,575,509 |
| Stories: | 8,713,377 |
Whistler Blowers, Insiders

