How Much Term Cover Do You Need As An NRI Supporting Parents In India?
Every month, a chunk of your salary in Dubai or Singapore lands in your parents’ account back in India before you even think about your own rent. You have term cover already, bought years ago when you first started working abroad, but it was never actually built around the fact that two people back home depend on that transfer arriving every single month.
If something happened to you tomorrow, would that number even survive?
What Makes This Calculation Different From a Standard Term Cover Estimate?
Most cover calculators ask for your annual income and multiply it by a factor, which works fine when you are protecting a spouse and kids who share your household expenses.
Supporting parents is a separate, standalone obligation with its own number, its own timeline, and its own risk if it goes unfunded.
You are not replacing a household income here; you are replacing a fixed transfer that has to keep landing in a specific account every month, regardless of what else your policy is covering.
How Much Are You Actually Sending Home Each Year?
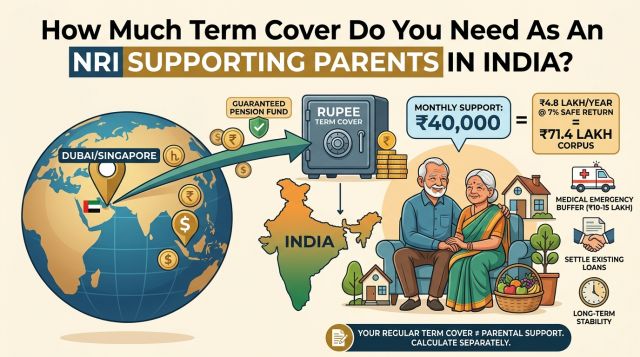
Start with the actual number, not a guess. If you send your parents ₹40,000 a month, that is ₹4.8 lakh a year, and that figure is your baseline.
Round it to something clean, say ₹5 lakh a year, and treat medical expenses, festival costs, and any small extras you cover separately as part of that same number rather than pretending they do not exist.
How Do You Turn That Yearly Amount Into a Lump Sum Figure?
This is where most people guess, and most calculators skip the actual math. You need a lump sum large enough that, placed somewhere safe, it throws off ₹5 lakh a year in income without your parents ever touching the principal, since you have no idea how many years that support actually needs to last.
Using a conservative return of around 7%, which is roughly what a senior citizen fixed deposit pays right now, the math looks like this. Divide ₹5,00,000 by 0.07, and you get around ₹71,40,000.
That is the corpus that generates your parents’ annual support forever at a safe rate, not a rough multiple of your salary that may or may not match what they actually need every year.
What Else Should Get Added to That Number?
The income replacement corpus covers routine support, not a crisis. A serious hospitalization for either parent can run into several lakhs in a short window. That cost should sit on top of ₹71,40,000, not inside it, since drawing down the income-generating corpus to pay a hospital bill defeats its whole purpose.
| What to Add | Rough Amount to Plan For | Why It Sits Separately |
| Emergency medical buffer | ₹10 to ₹15 lakh | Hospitalization costs arrive as one large bill, not monthly |
| Any loan or liability tied to your parents | Outstanding balance in full | This is a fixed, known number, not an estimate |
| Existing savings already earmarked for them | Subtract this from your total | Reduces how much new cover you actually need |
Does Buying Cover in Rupees Actually Matter Here?
Yes, more than people realize. A term insurance plan bought in India pays out in rupees, which means the amount that lands with your parents is not exposed to currency swings the way a foreign policy or a foreign investment account would be.
If you are earning in dirhams or dollars and the obligation you are protecting is entirely rupee-denominated, the payout removes one layer of uncertainty completely, since your parents never have to convert anything or absorb an exchange rate move at the worst possible time.
Working out this kind of cover is exactly why term insurance for NRI applicants exists as its own category, since the application, premium payment, and payout process are all built around someone living and earning outside India while the people depending on the policy live entirely inside it.
Should This Replace the Cover You Already Have for Your Own Family?
No, it sits beside it. If you also have a spouse or children depending on your income, that obligation gets calculated on its own, typically using an income multiple rather than the capitalization method used above, since a household’s ongoing expenses behave differently from a fixed transfer to two people.
The two numbers get added together, not compared against each other, because both obligations exist at the same time and both need to survive if you are not there to fund them.
Whichever term insurance plan you already hold was most likely priced and sized around that first number alone, so it is worth checking whether it was ever meant to stretch far enough to cover the second one too.
What Should You Actually Do With This Number?
Run your own version of this math with your actual monthly transfer amount instead of borrowing someone else’s estimate, since a number based on your parents’ real expenses is the only one that actually protects them.
Once you have that figure, check it against your existing sum assured, and if it falls short, treat the gap as unfinished business rather than something to revisit later.
Parents rarely tell their children exactly how much they depend on that monthly transfer, which is exactly why the number needs to be calculated properly once, rather than guessed at and hoped to be enough.
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
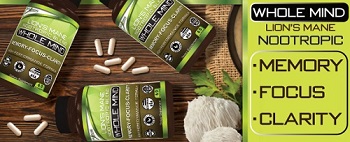
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,833,423,279 |
| Stories: | 8,712,532 |
Whistler Blowers, Insiders

